OpenAI, Anthropic & the New Compute Power Structure

Why the frontier-model race is becoming a contest over capital, cloud distribution, custom silicon, and infrastructure optionality.

Solten & Co. Research Report
Updated: August 20, 2026
Research universe: AI Infrastructure / Software AI / Capital & Deals

Research Passport

  • Publication type: Flagship Research Report
  • Publication version: 1.0
  • Published/updated: August 20, 2026
  • Evidence cut-off: August 20, 2026
  • Research universe: AI Infrastructure / Software AI / Capital & Deals
  • Estimated reading time: ~25 minutes
  • Original research exhibits: 3
  • Primary and high-quality sources: 17+

Intended audience: investors, family offices, venture and growth funds, AI infrastructure operators, strategy leaders and other decision-makers evaluating frontier AI economics. 

Key Findings

  1. Frontier AI is becoming an industrial system, not merely a software-model competition. Capital, power, data centers, silicon, cloud infrastructure, frontier models and distribution are now tightly coupled.


  1. The old “OpenAI is locked into Azure” narrative is no longer an adequate description of the market. Microsoft remains central, but OpenAI has deliberately built infrastructure and capital optionality across AWS, NVIDIA, Oracle, CoreWeave and other partners while renegotiating exclusivity.


  1. Anthropic’s multi-provider strategy has become materially larger than the roughly $50 billion compute picture often repeated in older analysis. By 2026, its disclosed relationships span AWS Trainium, Google/Broadcom TPUs, Microsoft Azure/NVIDIA capacity, SpaceX GPU infrastructure and additional infrastructure programs.


  1. Strategic AI transactions increasingly combine equity, compute purchase commitments, cloud distribution, IP/model access and commercial participation. Headline “investment” values can therefore be misleading unless the economic layers are separated.


  1. Long-term compute commitments deserve to be analyzed as quasi-fixed strategic obligations. The central risks are not only model performance but also demand, utilization, silicon obsolescence, falling compute prices, capital dependence, and counterparty concentration.

Table of Contents

  1. The Source Thesis — What the Sources Get Right
  2. OpenAI–Microsoft: The Original Strategic Flywheel
  3. Revenue Sharing: Real, Material — but Frequently Misdescribed
  4. The Biggest Update: OpenAI Is No Longer Simply “Locked into Azure”
  5. OpenAI’s AWS Pivot: From Azure Dependency to Infrastructure Portfolio
  6. Anthropic: Multi-Cloud as Strategy, Not Temporary Compromise
  7. Anthropic’s 2026 Scale-Up Makes the Original Numbers Obsolete
  8. Consumer vs. Enterprise: Useful Distinction, Weak Precision
  9. The Economics: The Real Constraint Is Not “Model Quality” but Cost of Intelligence
  10. The New Strategic Map: Reciprocal Dependence, Not Simple Cloud Control
  11. Capital Is Becoming Part of the Compute Contract
  12. Compute Commitments Are Emerging as a Form of Strategic Debt
  13. What the 2026 Market Says About Anthropic vs. OpenAI
  14. What to Watch Next — Investor Monitoring Framework
  15. Solten & Co. View

Scope & Methodology

Research question. This report examines how the strategic and economic relationships surrounding OpenAI and Anthropic have changed the competitive structure of frontier AI, with particular attention to capital, cloud distribution, compute commitments, silicon strategy, contractual optionality, and infrastructure dependence.

Scope. The report focuses on publicly disclosed or credibly reported relationships involving OpenAI, Anthropic, Microsoft, Amazon/AWS, Google, NVIDIA and selected infrastructure providers. It is not intended as a comprehensive valuation of either OpenAI or Anthropic, nor as an investment recommendation.

Evidence hierarchy. Priority is given to company disclosures, partner announcements, and other primary evidence. High-quality financial reporting is used where material commercial terms are not publicly disclosed. The report avoids treating media-reported terms as audited company facts.

Evidence classes used in this report:

DISCLOSED FACT — directly supported by a primary or authoritative source.

REPORTED TERM — reported by a credible secondary source but not independently disclosed by the relevant counterparty.

ESTIMATE — a quantitative or qualitative assessment based on incomplete public information.

SOLTEN & CO. INTERPRETATION — our synthesis, inference, or analytical conclusion.

Limitations. Large AI infrastructure agreements are unusually difficult to compare. A dollar investment, a multi-year compute purchase commitment, an “up to” gigawatt capacity announcement, and realized installed/utilized capacity are different economic objects. This report therefore avoids combining unlike commitments into a single headline total unless the units and assumptions are explicitly comparable.

What Changed

The sources captured an important structural shift toward infrastructure control, but several of its strongest claims have already aged materially.

OpenAI is no longer well described as a single-cloud, Azure-locked company. Its Microsoft relationship remains strategically important, yet exclusivity has been relaxed and major AWS, NVIDIA, and other infrastructure relationships now create meaningful supplier optionality.

Anthropic’s compute footprint has expanded far beyond the earlier multi-cloud figures frequently cited in 2025-era analysis. The company’s 2026 agreements make infrastructure diversification itself a core strategic capability.

The competitive framing has also changed. The relevant question is no longer simply whether hyperscalers “control” AI labs. The evidence points to reciprocal dependence: model labs need capital and compute, while hyperscalers and silicon vendors need frontier labs as anchor tenants, distribution engines, and validation customers for custom infrastructure.

Finally, the economic object called an “AI investment” is increasingly composite. Equity capital, compute commitments, distribution rights, model/IP access, and commercial revenue participation may sit inside the same strategic relationship. That makes transaction decomposition essential for serious investment analysis.

Executive Summary

The useful insight in the sources is that the frontier-model race can no longer be understood primarily as a benchmark contest. Compute, cloud distribution, capital structure, custom silicon, enterprise access, and contractual flexibility have become strategic variables in their own right.

But the market has moved materially since many of the arrangements described in the sources were formed. The most important update is that OpenAI is no longer accurately described as being structurally locked into Microsoft Azure in the old sense. Microsoft remains a major shareholder and a central strategic partner, but the relationship was progressively loosened in 2025 and 2026. OpenAI now has major compute and distribution relationships with AWS and NVIDIA, can serve products through other cloud providers under the amended Microsoft agreement, and has committed to large-scale multi-provider infrastructure. Microsoft’s OpenAI IP license is now non-exclusive, while OpenAI’s revenue share to Microsoft continues through 2030 subject to a cap.

Anthropic, meanwhile, has gone even further in constructing a deliberately diversified infrastructure strategy. AWS remains its primary cloud and training partner, but Anthropic also uses Google TPUs and NVIDIA GPUs, has Claude available across AWS Bedrock, Google Vertex AI and Microsoft Azure Foundry, and has accumulated multi-gigawatt capacity agreements across providers. In 2026, it also added SpaceX GPU capacity and expanded AWS and Google commitments dramatically.

This changes the central analytical conclusion. The emerging structure is not simply “hyperscalers own the AI labs.” It is better understood as a dense network of reciprocal dependencies: labs need capital, power, and compute; hyperscalers need frontier models to drive cloud demand, custom-silicon adoption, and enterprise AI distribution; chip vendors need anchor customers; investors need exposure to the model layer; and model companies increasingly seek infrastructure optionality to avoid strategic dependence on any single supplier.

The long-term advantage may therefore accrue not to one layer alone, but to actors that control scarce infrastructure while preserving bargaining power across the stack.

1. The Source Thesis — What the Source Gets Right

The source argues that the AI industry has entered a “middle game” in which model quality remains important but infrastructure control, compute access, and cloud distribution increasingly determine who can operate at frontier scale.

That framing is directionally correct.

Training and serving frontier models has become a capital-intensive industrial activity. The relevant inputs are no longer only algorithms and training data. They include data-center capacity, power, accelerators, networking, memory, inference infrastructure, custom silicon, cloud procurement and long-term financing. The frontier-model companies are therefore becoming unusually intertwined with hyperscalers, semiconductor vendors and infrastructure financiers.

OpenAI itself described the 2026 scaling problem in three words: “compute, distribution, and capital.” In February 2026, when announcing $110 billion of new investment, the company said leadership in the next phase would be defined by who could scale infrastructure fast enough to meet demand and convert that capacity into products used at global scale.

This is an important shift in how the sector should be analyzed. A useful company model can no longer stop at product quality, model benchmarks, or subscription growth. It must also ask:

  • Who finances the company’s infrastructure?
  • Which cloud providers distribute the models?
  • What silicon does the company depend on?
  • How much power and capacity has it contracted?
  • Which agreements are exclusive?
  • Which agreements create minimum-purchase or long-term compute obligations?
  • Who receives revenue shares?
  • Where can the company switch providers, and at what economic or technical cost?
  • What does the infrastructure partner receive beyond direct cloud revenue — equity appreciation, custom-silicon validation, enterprise distribution or strategic leverage?

That is the stronger framework behind the source.

2. OpenAI–Microsoft: The Original Strategic Flywheel

Microsoft’s relationship with OpenAI began as a strategic shortcut into frontier AI. Microsoft invested $1 billion in OpenAI in 2019 and subsequently expanded the relationship through additional capital, cloud capacity, IP rights, and distribution arrangements.

The logic was powerful on both sides.

OpenAI received access to a hyperscaler capable of financing and deploying enormous compute clusters. Microsoft received privileged access to frontier-model IP, a differentiated Azure AI offering, and the ability to incorporate OpenAI technology across products such as Copilot and Microsoft 365.

For several years, this created a reinforcing system:

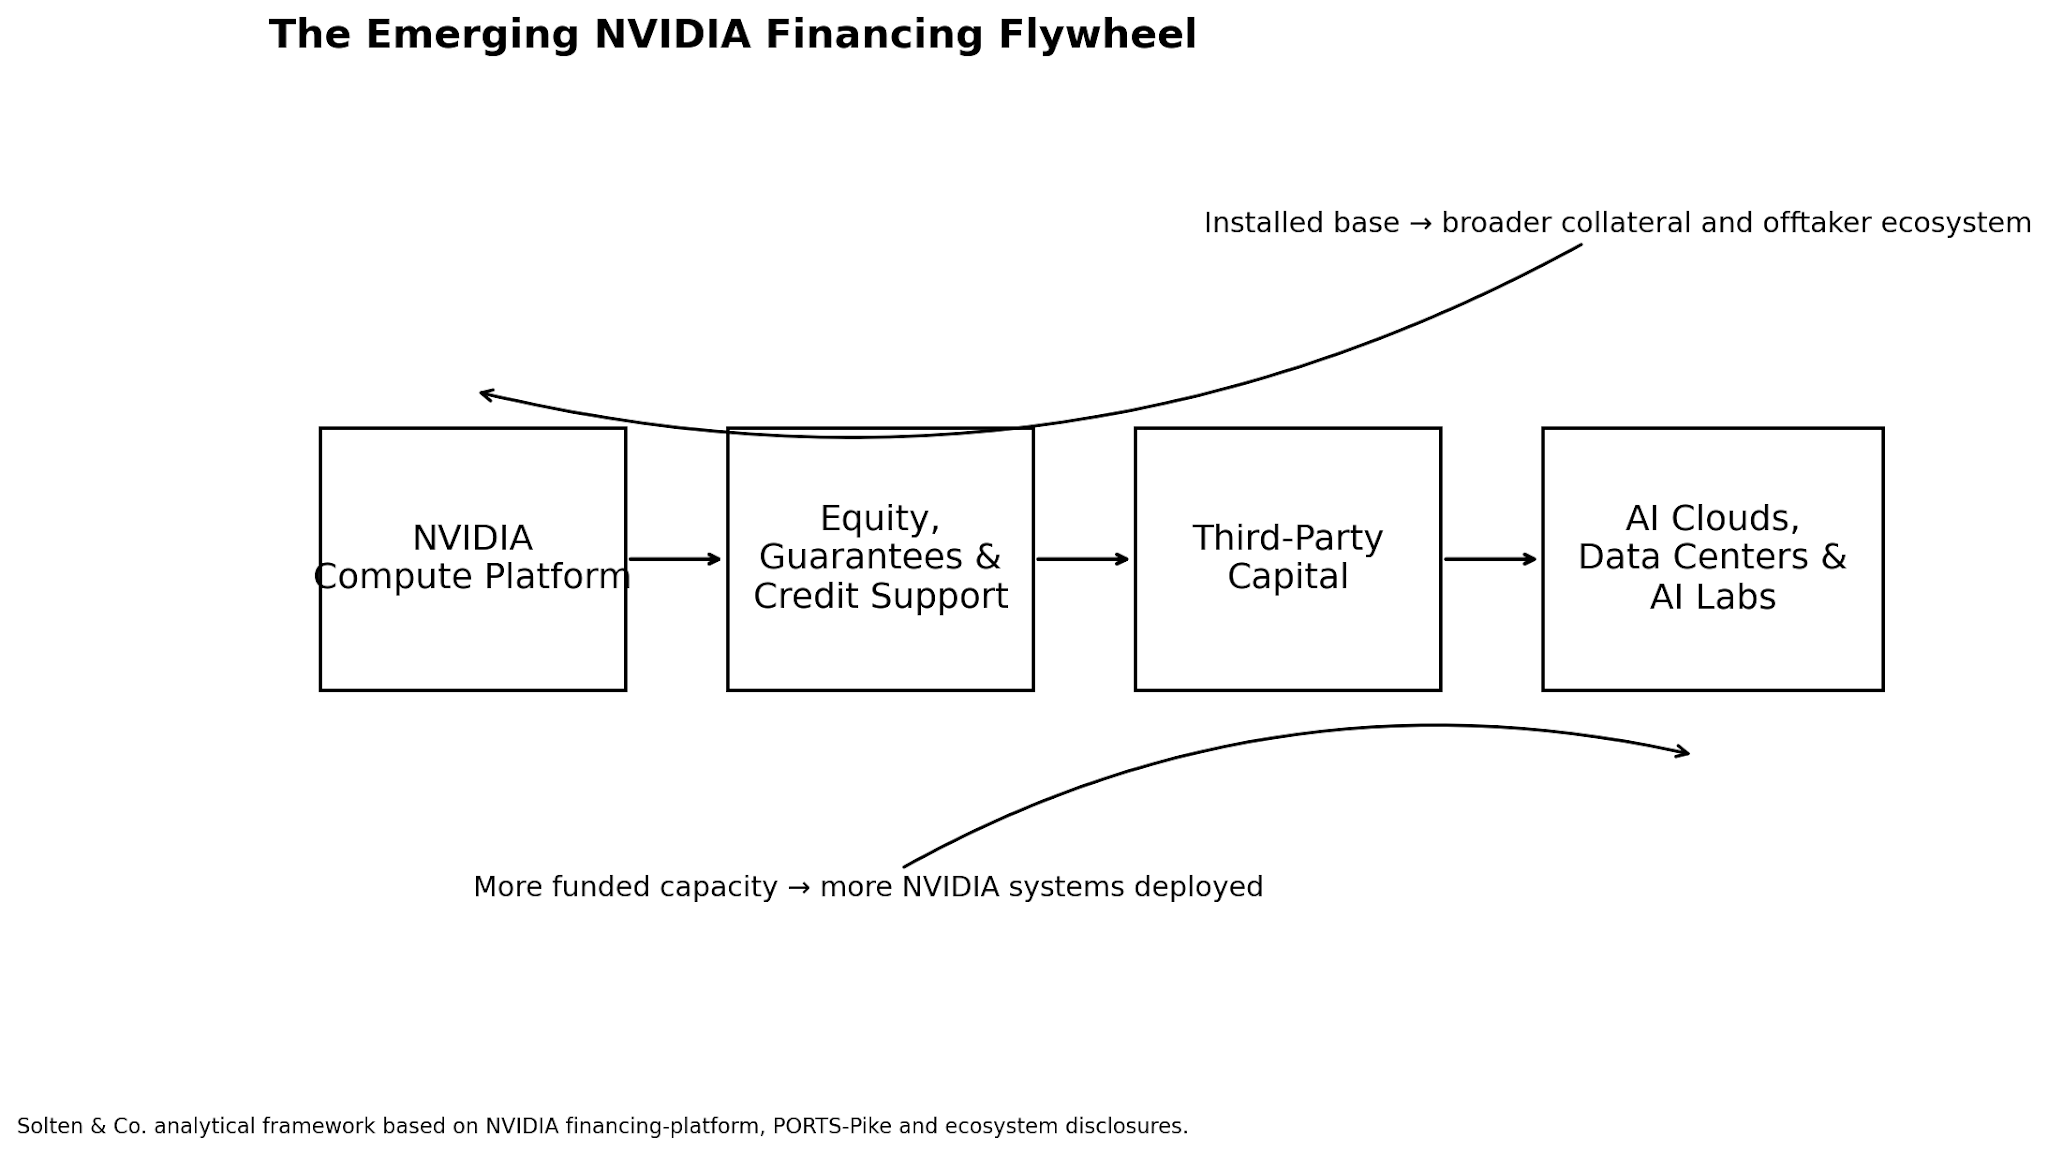
Microsoft capital → OpenAI compute demand → Azure revenue → OpenAI model improvement → Microsoft product differentiation → enterprise Azure demand.

The structure also made Microsoft simultaneously investor, infrastructure provider, distributor, and commercial beneficiary.

In October 2025, OpenAI completed a major recapitalization. Microsoft’s investment in OpenAI Group PBC was valued at approximately $135 billion, representing roughly 27% of the company on an as-converted diluted basis. OpenAI’s nonprofit parent — the OpenAI Foundation — held 26%, while employees and other investors held the remaining 47%.

This part of the source is substantially correct: Microsoft ended up with an economic stake in OpenAI worth about $135 billion, although the precise percentage is better stated as roughly 27%, not a loose 26–30% range.

3. Revenue Sharing: Real, Material — but Frequently Misdescribed

The Microsoft–OpenAI relationship has included revenue-sharing arrangements flowing in both directions.

Historically, reporting indicated that OpenAI agreed to share approximately 20% of revenue with Microsoft through 2030. In 2025, Reuters reported that OpenAI planned to reduce Microsoft’s share over time, but the companies subsequently confirmed that the revenue-sharing arrangement remained in place.

The structure changed again in April 2026.

Microsoft stated that it would no longer pay a revenue share to OpenAI. Revenue-share payments from OpenAI to Microsoft would continue through 2030 at the same percentage, but subject to an overall cap. Reuters subsequently reported, citing The Information, that the total future revenue-sharing obligation had been capped at approximately $38 billion.

This is materially different from the older picture in which reciprocal revenue sharing was treated as a relatively stable permanent mechanism.

The investment implication is important. Microsoft still has several distinct ways to benefit economically from OpenAI:

  1. Equity appreciation through its roughly 27% ownership position.
  2. Revenue-share payments from OpenAI through 2030, subject to the agreed cap.
  3. Azure consumption and broader infrastructure revenue.
  4. Product differentiation and enterprise distribution through Microsoft’s own AI products.
  5. Strategic spillovers into Microsoft’s cloud and developer ecosystem.

The source’s claim that Microsoft captured $865 million through revenue sharing in the first nine months of 2025 should be treated as an externally reported figure rather than a primary-source fact. We did not find a first-party Microsoft or OpenAI disclosure confirming that exact number. It may be useful context, but it should not be presented as audited public financial disclosure.

4. The Biggest Update: OpenAI Is No Longer Simply “Locked into Azure”

This is where the source narrative is now most outdated.

In early 2025, Microsoft still described the OpenAI API as exclusive to Azure and retained a right of first refusal on new compute capacity. The October 2025 agreement preserved Azure API exclusivity and Microsoft’s exclusive IP rights until AGI, while also allowing OpenAI greater freedom to build additional compute elsewhere.

By February 2026, OpenAI and Microsoft jointly clarified that Azure remained the exclusive cloud provider for stateless OpenAI APIs, even while OpenAI pursued additional compute relationships.

Then, in April 2026, the relationship changed more fundamentally.

Microsoft announced an amended agreement under which:

  • Microsoft remains OpenAI’s primary cloud partner.
  • OpenAI products generally ship first on Azure, unless Microsoft cannot or chooses not to support the required capabilities.
  • OpenAI can serve its products to customers through any cloud provider.
  • Microsoft’s license to OpenAI models and products through 2032 became non-exclusive.
  • Microsoft stopped paying revenue share to OpenAI.
  • OpenAI’s revenue-share payments to Microsoft continue through 2030, subject to a cap.

This is a major strategic shift.

The original Microsoft–OpenAI partnership was based on deep bilateral dependence. The revised structure increasingly resembles a major strategic partnership inside a broader multi-cloud and multi-capital network.

OpenAI’s subsequent AWS relationship makes this concrete.

5. OpenAI’s AWS Pivot: From Azure Dependency to Infrastructure Portfolio

In November 2025, OpenAI and AWS announced a $38 billion multi-year agreement under which OpenAI would use AWS infrastructure containing hundreds of thousands of NVIDIA GPUs.

In February 2026, that relationship expanded dramatically.

Amazon committed to invest $50 billion in OpenAI. OpenAI and AWS expanded their infrastructure agreement by another $100 billion over eight years. OpenAI committed to consume approximately 2 gigawatts of Trainium capacity, spanning Trainium3 and Trainium4, beginning to ramp in 2027.

AWS also became the exclusive third-party cloud distribution provider for OpenAI Frontier, while OpenAI and Amazon agreed to co-develop a stateful runtime environment in Amazon Bedrock and customized models for Amazon applications.

By June 2026, OpenAI frontier models and Codex were generally available on AWS.

OpenAI also announced 3 GW of dedicated NVIDIA inference capacity and 2 GW of training capacity on Vera Rubin systems, in addition to infrastructure already running across Microsoft, Oracle Cloud Infrastructure and CoreWeave.

The strategic implication is clear: OpenAI is deliberately creating infrastructure optionality.

This does not make Microsoft unimportant. Microsoft remains the primary cloud partner, major shareholder, and revenue-share recipient. But OpenAI now has multiple meaningful infrastructure and capital relationships, reducing the old single-provider concentration risk and increasing its bargaining flexibility.

6. Anthropic: Multi-Cloud as Strategy, Not Temporary Compromise

Anthropic’s infrastructure model has historically been more diversified than OpenAI’s.

AWS became Anthropic’s primary cloud provider for mission-critical workloads in 2023. In November 2024, Amazon added another $4 billion investment, bringing its total at that time to $8 billion, while AWS became Anthropic’s primary cloud and training partner.

Anthropic simultaneously deepened its Google relationship. In October 2025, it announced plans to use up to one million Google TPUs, with more than one gigawatt of capacity expected online in 2026. Anthropic explicitly described its compute strategy as diversified across Google TPUs, AWS Trainium, and NVIDIA GPUs.

In November 2025, Anthropic expanded into Microsoft Azure as well. Microsoft committed to invest up to $5 billion in Anthropic and NVIDIA up to $10 billion, while Anthropic committed to purchase $30 billion of Azure compute capacity. Claude became available in Microsoft Foundry, giving Anthropic distribution across AWS Bedrock, Google Vertex AI and Microsoft Azure.

This three-cloud distribution position was strategically unusual and important.

7. Anthropic’s 2026 Scale-Up Makes the Original Numbers Obsolete

The source cites Anthropic’s compute commitments at roughly $50 billion. That figure is no longer a useful description of current exposure.

In April 2026, Anthropic announced a new agreement with Google and Broadcom for multiple gigawatts of next-generation TPU capacity, expected to begin coming online in 2027. Anthropic said this was its most significant compute commitment to date.

Later that month, Anthropic expanded its AWS relationship to secure up to 5 GW of new capacity and committed more than $100 billion over ten years to AWS technologies. It said it was already using more than one million Trainium2 chips and that Amazon remained its primary training and cloud provider.

Amazon simultaneously invested another $5 billion, with the possibility of up to $20 billion more in future investment.

Anthropic also added more than 300 MW of NVIDIA GPU capacity through SpaceX’s Colossus infrastructure.

By mid-2026, Anthropic’s infrastructure strategy included:

  • AWS Trainium — primary cloud/training relationship, up to 5 GW of new capacity.
  • Google/Broadcom TPUs — multi-gigawatt next-generation capacity.
  • Microsoft Azure/NVIDIA — $30 billion Azure capacity relationship.
  • SpaceX — more than 300 MW of NVIDIA GPU capacity.
  • Fluidstack — part of a broader $50 billion U.S. infrastructure program.

The strategic pattern is not merely “multi-cloud.” It is active procurement diversification across cloud vendors, silicon architectures, and physical infrastructure providers.

8. Consumer vs. Enterprise: Useful Distinction, Weak Precision

The source contrasts OpenAI as consumer-driven and Anthropic as enterprise-driven. This distinction is broadly useful, but the exact percentages cited in the source should be treated cautiously.

For OpenAI, Reuters reported in late 2025 that roughly 30% of revenue came from enterprise customers, implying that the majority still came from consumer-oriented products, particularly ChatGPT subscriptions. This supports the directional claim that OpenAI was more consumer-weighted than Anthropic.

For Anthropic, multiple sources confirm unusually strong enterprise adoption. In 2025, Reuters described Anthropic’s revenue acceleration as being driven by business demand, particularly coding. Anthropic reported more than 300,000 business customers in October 2025 and more than 500 customers spending over $1 million annualized by early 2026; that figure exceeded 1,000 by April 2026.

However, the claim that “85% of Anthropic revenue comes from B2B API calls” is not supported by the first-party sources reviewed here. Anthropic is clearly enterprise-heavy, but its revenue mix now includes subscriptions, Claude Code, direct enterprise contracts, API activity and hyperscaler distribution. A single percentage may be both unverifiable and quickly obsolete.

The deeper point is more important than the percentages:

OpenAI built a massive direct consumer distribution engine first, then pushed aggressively into enterprise.

Anthropic built stronger early positioning in enterprise and developer workflows, especially coding, while using broad hyperscaler distribution to reach customers inside existing cloud environments.

By 2026, both companies are converging toward enterprise distribution, making the old consumer-versus-enterprise binary less clean.

9. The Economics: The Real Constraint Is Not “Model Quality” but Cost of Intelligence

The source says OpenAI spends roughly $2 for every $1 of revenue. That framing is too simplistic for serious analysis.

OpenAI’s financial profile is undeniably capital-intensive, but reported figures must distinguish cash spending, compute costs, operating losses, and non-cash restructuring charges.

The Financial Times reported that OpenAI generated approximately $13 billion of revenue in 2025 while spending $34 billion. It reported a $39 billion net loss, but roughly $30 billion of that was a non-cash charge related to the prior investor structure. Excluding that charge and other non-cash items, operational losses were reported at around $8 billion.

This means the simple statement “OpenAI spends $2 for every $1 earned” may capture the scale of gross cash requirements at some point, but it is not a reliable representation of ongoing operating unit economics.

The more interesting economic question is how quickly inference costs decline relative to usage growth.

Frontier AI has a structural tension:

Better models → more demand → more inference → more infrastructure spending.

If price per unit of intelligence falls faster than compute efficiency improves, revenue growth may not translate proportionally into margin expansion.

This is why custom silicon and infrastructure bargaining power matter so much.

AWS wants Trainium adoption because custom silicon can reduce dependence on NVIDIA and capture more of the economics inside AWS.

Google wants TPU scale for the same reason.

Microsoft wants OpenAI-driven Azure demand and deeper software integration.

NVIDIA wants long-duration demand visibility from the frontier labs.

The model labs want enough supplier diversity to prevent any single infrastructure provider from capturing too much of their margin.

10. The New Strategic Map: Reciprocal Dependence, Not Simple Cloud Control

The source’s broader takeaway — that hyperscalers may be the true winners — is plausible but incomplete.

Hyperscalers clearly occupy a privileged position because they control data-center footprints, power procurement, networking, cloud distribution, enterprise relationships, and increasingly custom silicon.

But frontier labs also possess leverage.

A leading model company can move enormous volumes of compute procurement, validate a new chip architecture, attract cloud customers, strengthen an enterprise AI platform, and create equity gains for strategic investors.

This creates reciprocal dependence.

Consider AWS and Anthropic.

Anthropic needs AWS infrastructure. But AWS also uses Anthropic as the flagship proof point for Trainium. Project Rainier and more than one million Trainium2 chips give Amazon a reference customer at a scale few others can provide. Anthropic therefore helps AWS validate a strategic attempt to reduce dependence on NVIDIA.

Likewise, OpenAI’s 2 GW Trainium commitment is strategically important to AWS’s custom-silicon business.

The model companies are not merely buyers. They are anchor tenants for an emerging AI industrial infrastructure.

11. Capital Is Becoming Part of the Compute Contract

A striking feature of the current market is the increasing overlap between investor and supplier roles.

Microsoft is both a major OpenAI shareholder and infrastructure partner.

Amazon is both a major Anthropic shareholder and Anthropic’s primary cloud provider. It is now also a $50 billion OpenAI investor and major OpenAI compute supplier.

Google is an Anthropic investor and TPU/cloud partner.

NVIDIA invests in both model companies while also supplying the accelerators on which much of the industry depends.

This creates a new analytical problem for investors: headline “investment” announcements cannot be evaluated independently from procurement commitments, cloud contracts, revenue-sharing agreements and supplier incentives.

A strategic investment may effectively subsidize future infrastructure consumption. A compute commitment may in turn secure capital, distribution, or silicon priority.

Therefore, future Solten & Co. deal analysis should separate at least five economic layers in AI transactions:

  1. Equity investment.
  2. Compute purchase commitments.
  3. Cloud distribution rights.
  4. IP/model licensing rights.
  5. Revenue-share or commercial participation rights.

Without separating these layers, reported transaction values can be misleading.

12. Compute Commitments Are Emerging as a Form of Strategic Debt

Long-term compute commitments are not debt in the legal accounting sense, but economically they can behave like quasi-fixed obligations.

A lab that contracts tens or hundreds of billions of dollars of future capacity is making a bet on continued demand growth, model economics, and capital availability.

This creates several risks:

Demand risk — future AI usage may grow more slowly than contracted capacity.

Price risk — compute prices may fall faster than expected, making old commitments expensive relative to market alternatives.

Technology risk — a contracted silicon architecture may become less competitive.

Capital risk — the company may need continuous financing to fund capacity before operating cash flow catches up.

Utilization risk — infrastructure economics deteriorate sharply if expensive capacity is underused.

Counterparty risk — hyperscalers and infrastructure providers become increasingly exposed to the financial health of a small group of frontier labs.

This is one of the most important areas for future investment research because the market often celebrates giant compute commitments as evidence of confidence while under-analyzing their downside asymmetry.

13. What the 2026 Market Says About Anthropic vs. OpenAI

The competitive picture changed dramatically in 2026.

Anthropic reported run-rate revenue above $30 billion in April 2026, up from approximately $9 billion at the end of 2025. Reuters reported in August 2026 that Anthropic’s annualized run rate had exceeded $65 billion by the end of July.

This is far beyond the scale implied in the source.

OpenAI remains enormous, with unmatched consumer awareness and major enterprise ambitions, but recent reporting suggests stronger competitive pressure from Anthropic in coding and enterprise workloads.

The investment lesson is not that Anthropic has definitively “won.” It is that infrastructure strategy and distribution architecture can materially affect commercial outcomes.

Anthropic’s ability to be present inside all three major cloud ecosystems reduced customer procurement friction and gave it multiple infrastructure paths.

OpenAI, initially more concentrated around Microsoft, has spent 2025–2026 building similar optionality through AWS, NVIDIA, Oracle, CoreWeave and Stargate.

The two firms are therefore converging toward a common strategic requirement: no frontier lab wants to depend on a single source of capital, compute, or distribution.

14. What to Watch Next — Investor Monitoring Framework

For investors analyzing frontier AI, cloud infrastructure or adjacent companies, the following metrics may now be more informative than benchmark leadership alone.

Infrastructure concentration

What percentage of training and inference depends on each provider?

Committed capacity

How much future compute, power, and data-center capacity is contractually committed?

Compute economics

What is the effective cost per training run, per inference token or per unit of delivered intelligence?

Silicon mix

How exposed is the company to NVIDIA versus Trainium, TPU or other accelerators?

Distribution breadth

Can the company sell through AWS, Azure, Google Cloud, and directly?

Revenue concentration

How dependent is growth on consumers, coding tools, API use or a small number of enterprise customers?

Capital dependency

How much external funding is required before free cash flow becomes plausible?

Strategic investor overlap

Are suppliers also shareholders? Do those relationships distort apparent pricing or economics?

Contract flexibility

Can the company shift workloads across providers when technology or economics change?

Infrastructure utilization

Are contracted gigawatts translating into monetized demand?

15. Solten & Co. View

The frontier AI market is evolving from a software race into an industrial system.

That system has at least six tightly coupled layers:

Capital → Power/Data Centers → Silicon → Cloud Infrastructure → Frontier Models → Applications/Distribution.

The key strategic question is no longer only who has the best model.

It is who can secure sufficient capital and infrastructure without surrendering too much economics or strategic flexibility to the companies supplying that infrastructure.

OpenAI’s 2025–2026 evolution is a case study in reducing dependency. Microsoft remains central, but OpenAI has steadily expanded into AWS, NVIDIA, and other infrastructure partners while renegotiating exclusivity.

Anthropic is a case study in diversified infrastructure from an earlier stage. AWS remains primary, but Anthropic has systematically maintained access to multiple clouds and silicon architectures.

The hyperscalers are likely to capture enormous value because the frontier-model boom drives cloud demand, custom-silicon adoption and enterprise AI distribution. But the idea that they will automatically own the economics is too simple.

The more likely equilibrium is a small number of frontier labs and infrastructure giants locked in reciprocal dependence, each attempting to diversify enough to preserve bargaining power.

For investors, the most underappreciated layer may be the contracts connecting them.

Those contracts — compute commitments, distribution rights, strategic investments, revenue shares and silicon partnerships — increasingly determine which companies have flexibility, which carry hidden obligations, and where economic value ultimately accrues.

Fact-Check: Selected Claims from the Source

Claim: Microsoft owns approximately 26–30% of OpenAI, worth about $135B.

Status: Substantially verified. Microsoft disclosed roughly 27%, valued at approximately $135B after the October 2025 recapitalization.

Claim: Microsoft receives roughly 20% of OpenAI revenue through 2030.

Status: Historically supported by reporting; the 2026 amended agreement kept the same percentage through 2030 but added a total cap. Reuters later reported the cap at approximately $38B.

Claim: OpenAI receives roughly 20% of Azure OpenAI/Bing AI revenue.

Status: Reciprocal revenue sharing existed historically, but this is now outdated. Microsoft said in April 2026 that it would no longer pay a revenue share to OpenAI.

Claim: OpenAI committed to purchase $250B of Azure services.

Status: Verified as an October 2025 incremental Azure commitment. However, the broader relationship has since changed materially, and OpenAI has added very large AWS and NVIDIA commitments.

Claim: Microsoft has exclusive API distribution rights until AGI.

Status: Outdated. This described the earlier structure. The April 2026 amendment materially relaxed exclusivity and made Microsoft’s IP license non-exclusive, while OpenAI gained the ability to serve products through other clouds.

Claim: Anthropic has approximately $50B in compute commitments across providers.

Status: Outdated. Anthropic’s 2026 commitments expanded far beyond this number, including more than $100B committed to AWS alone over ten years, multi-gigawatt Google capacity, $30B of Azure capacity and additional GPU infrastructure.

Claim: Anthropic uses up to 1M Google TPUs and around 1 GW of Google capacity.

Status: Verified as the October 2025 announced plan. The Google/Broadcom relationship expanded again in April 2026 into multiple gigawatts of next-generation TPU capacity.

Claim: Amazon invested $8B in Anthropic and AWS is its primary cloud provider.

Status: Verified historically. Amazon’s total investment has since increased, and AWS remains Anthropic’s primary cloud and training provider.

Claim: Anthropic is available through AWS Bedrock, Google Vertex AI and Azure Foundry.

Status: Verified. Anthropic describes Claude as the only frontier AI model available across all three major cloud platforms.

Claim: OpenAI is ~73% consumer revenue and Anthropic ~85% B2B API revenue.

Status: Directionally plausible but not sufficiently supported at those exact percentages by primary evidence reviewed. Reuters reported roughly 30% enterprise revenue for OpenAI in late 2025 and consistently described Anthropic growth as enterprise-led. Exact percentages should not be used without a dated underlying source.

Claim: OpenAI spends roughly $2 for every $1 of revenue.

Status: Oversimplified. OpenAI is highly cash-intensive, but reported losses include major non-cash items and changing compute economics. Use specific period financial data instead of a permanent ratio.

Primary and High-Quality Sources

Microsoft — The next chapter of the Microsoft–OpenAI partnership, Oct. 28, 2025

https://blogs.microsoft.com/blog/2025/10/28/the-next-chapter-of-the-microsoft-openai-partnership/

OpenAI — Our Structure

https://openai.com/our-structure/

OpenAI/Microsoft — Joint Statement, Feb. 27, 2026

https://openai.com/index/continuing-microsoft-partnership/

Microsoft — The next phase of the Microsoft–OpenAI partnership, Apr. 27, 2026

https://blogs.microsoft.com/blog/2026/04/27/the-next-phase-of-the-microsoft-openai-partnership/

Reuters — OpenAI/Microsoft revenue-share cap report, May 12, 2026

https://www.reuters.com/technology/openai-cap-microsoft-revenue-sharing-38-billion-information-reports-2026-05-12/

OpenAI — AWS and OpenAI multi-year strategic partnership, Nov. 3, 2025

https://openai.com/index/aws-and-openai-partnership/

OpenAI — OpenAI and Amazon strategic partnership, Feb. 27, 2026

https://openai.com/index/amazon-partnership/

OpenAI — Scaling AI for everyone, Feb. 27, 2026

https://openai.com/index/scaling-ai-for-everyone/

OpenAI — Frontier models and Codex available on AWS, Jun. 1, 2026

https://openai.com/index/openai-frontier-models-and-codex-are-now-available-on-aws/

Anthropic — Powering the next generation of AI development with AWS, Nov. 22, 2024

https://www.anthropic.com/news/anthropic-amazon-trainium

Anthropic — Expanding our use of Google Cloud TPUs and Services, Oct. 23, 2025

https://www.anthropic.com/news/expanding-our-use-of-google-cloud-tpus-and-services

Anthropic — Microsoft, NVIDIA and Anthropic strategic partnerships, Nov. 2025

https://www.anthropic.com/news/microsoft-nvidia-anthropic-announce-strategic-partnerships

Anthropic — Google/Broadcom next-generation compute expansion, Apr. 6, 2026

https://www.anthropic.com/news/google-broadcom-partnership-compute

Anthropic — Amazon compute expansion, Apr. 20, 2026

https://www.anthropic.com/news/anthropic-amazon-compute

Anthropic — Higher limits and SpaceX compute partnership, 2026

https://www.anthropic.com/news/higher-limits-spacex

Reuters — Anthropic annualized revenue reached $3B on business demand, May 30, 2025

https://www.reuters.com/business/anthropic-hits-3-billion-annualized-revenue-business-demand-ai-2025-05-30/

Reuters — Anthropic revenue run rate tops $65B, Aug. 17, 2026

https://www.reuters.com/technology/anthropic-revenue-run-rate-tops-65-billion-source-says-2026-08-17/

Financial Times — OpenAI spending hit $34B in 2025

https://www.ft.com/content/e15b0d7e-ff6b-4f16-ba7a-4068feddb828

Evidence & Publication Note

Publication-ready research report. The analysis separates disclosed facts, externally reported terms, and Solten & Co. interpretation, and includes original research exhibits covering selected compute capacity, partnership structure, and the evolution toward multi-provider infrastructure portfolios.

Research Exhibits

Exhibit 1 — Selected Announced Frontier-Lab Compute Capacity

The figures below capture disclosed capacity announcements, not directly comparable installed capacity. Timing, silicon, workload type, and “up to” language differ materially across agreements.
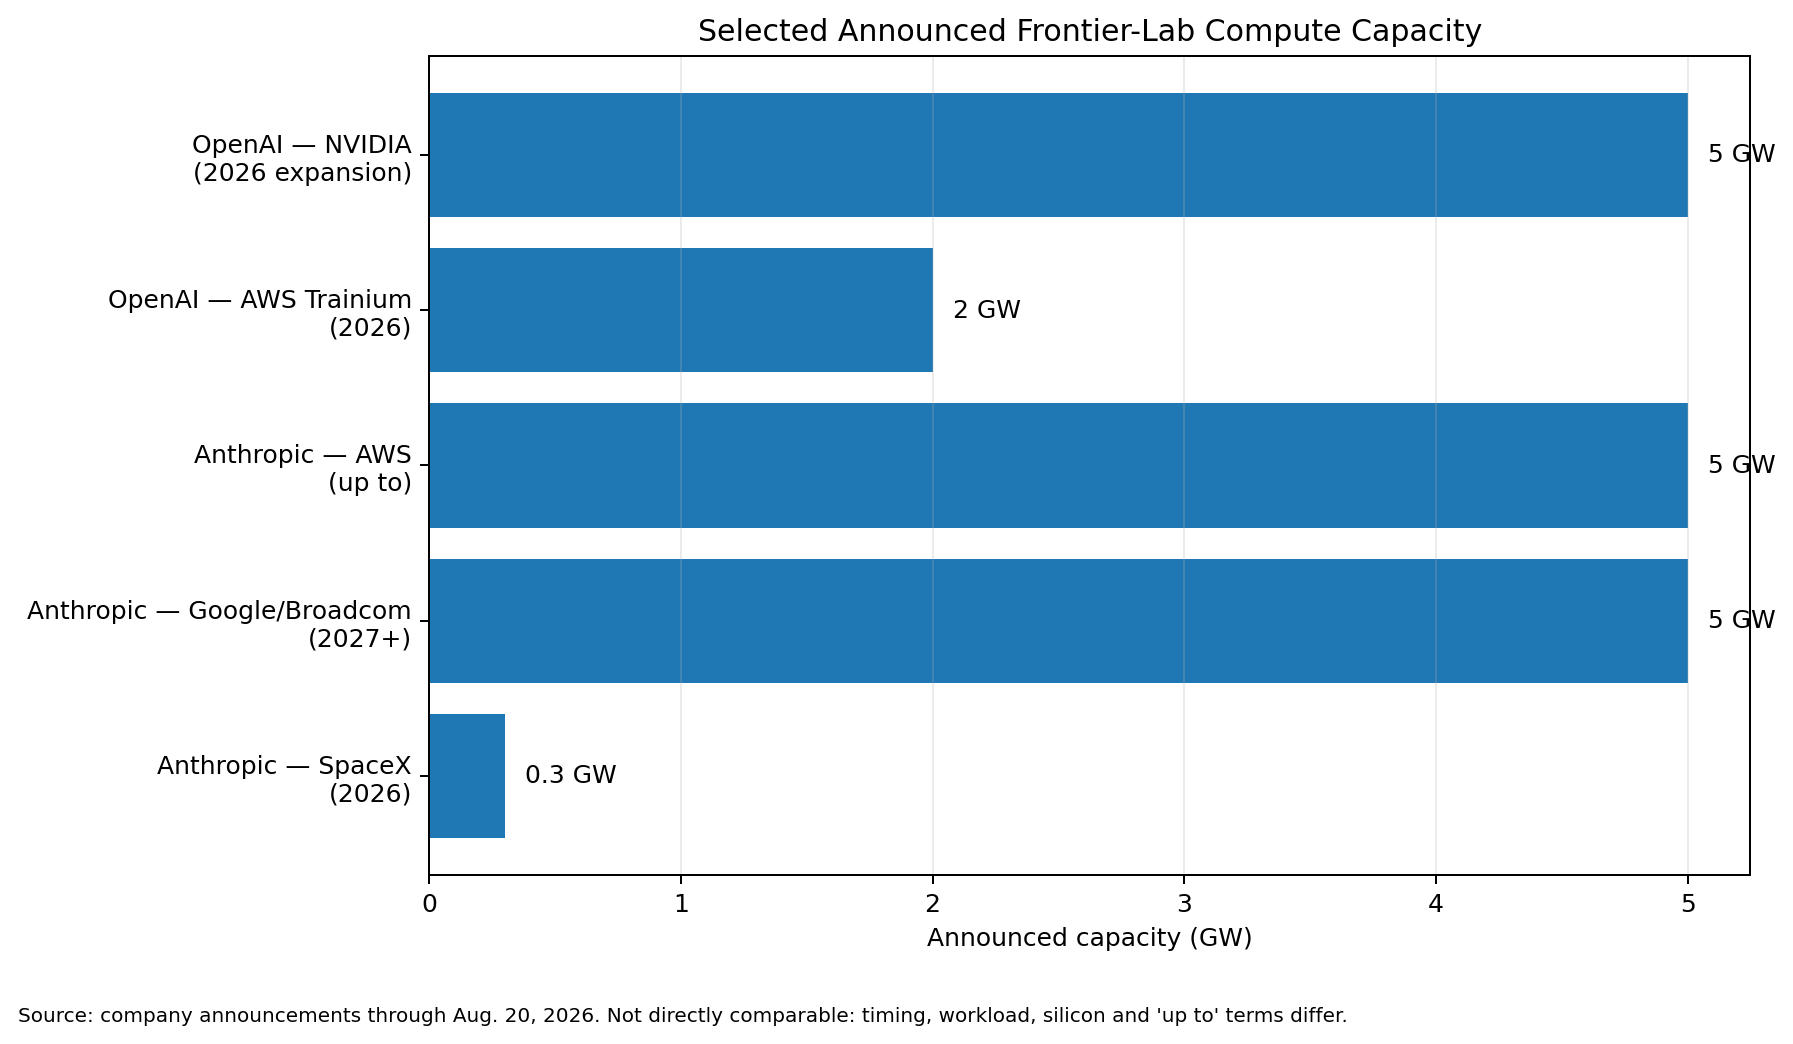
Exhibit 2 — AI Strategic Partnerships Are Multi-Layer Transactions

The same counterparty can simultaneously be an investor, compute supplier, distributor, model-access partner and commercial beneficiary. This is why headline investment values alone are poor representations of the underlying economics.
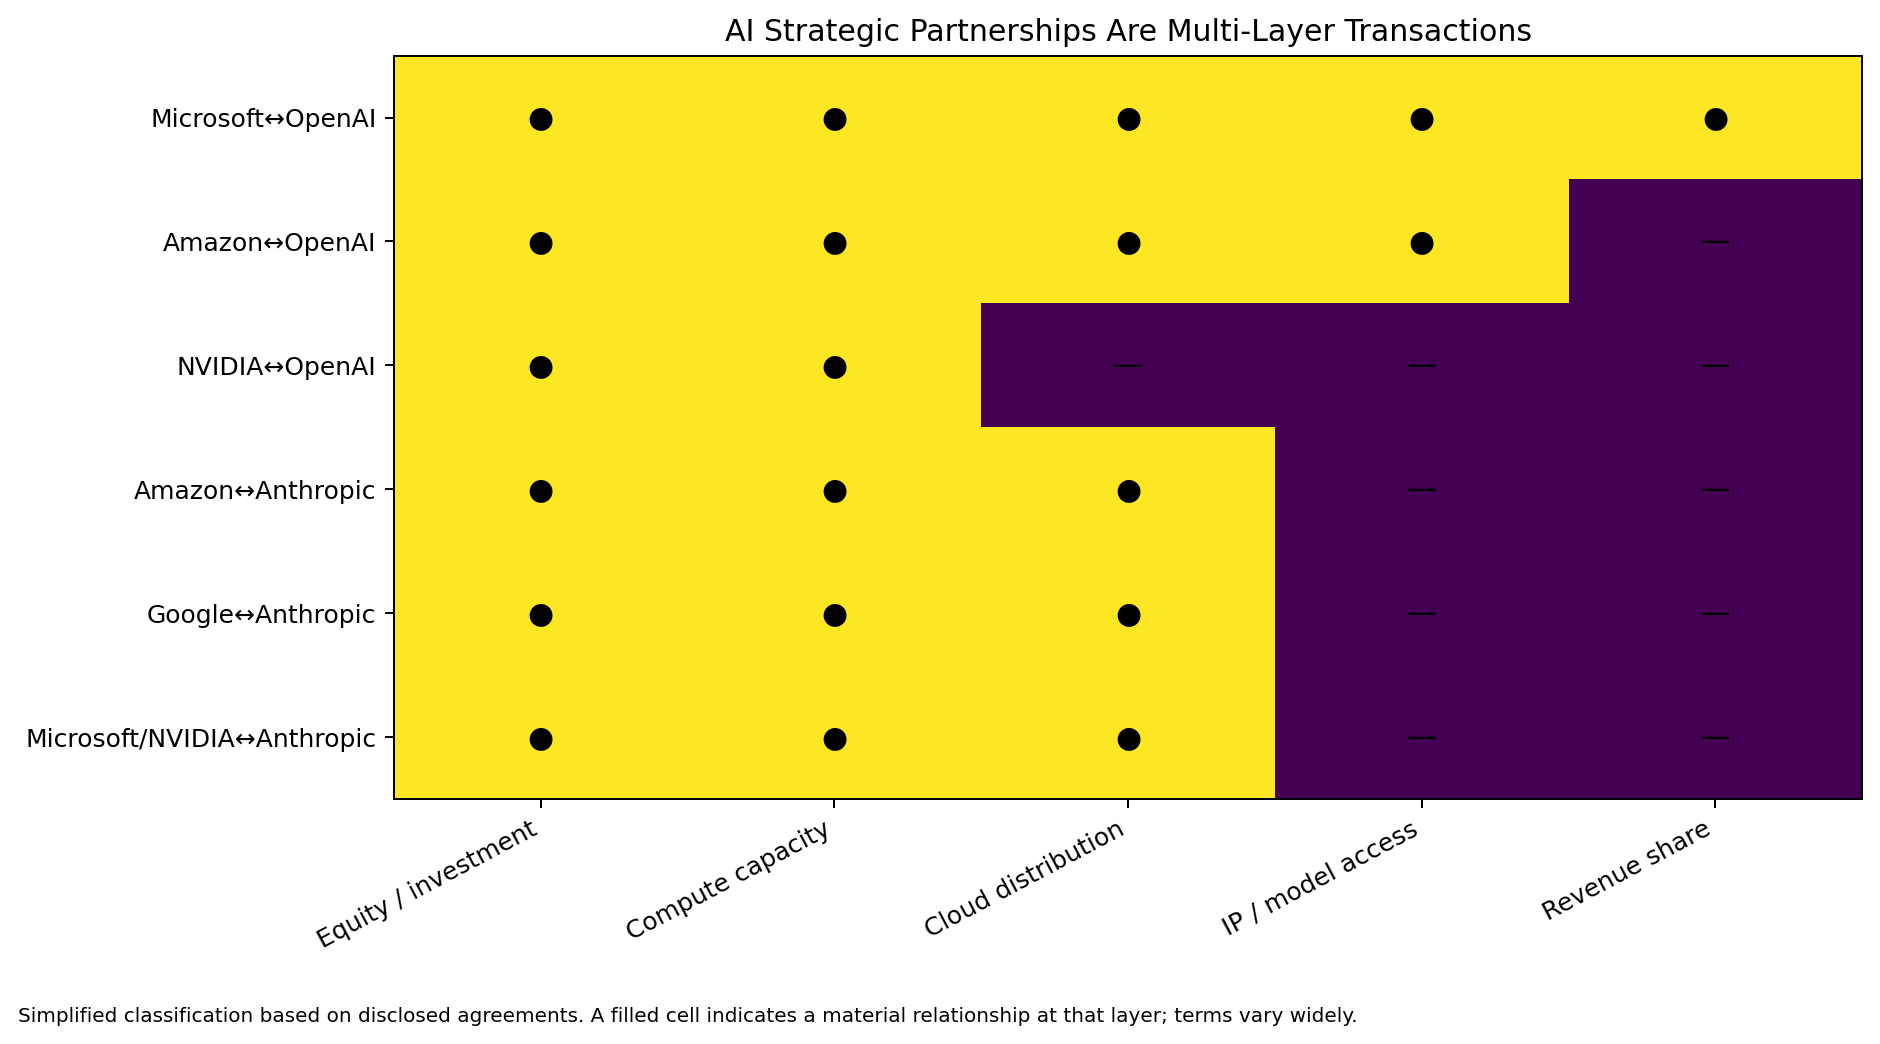
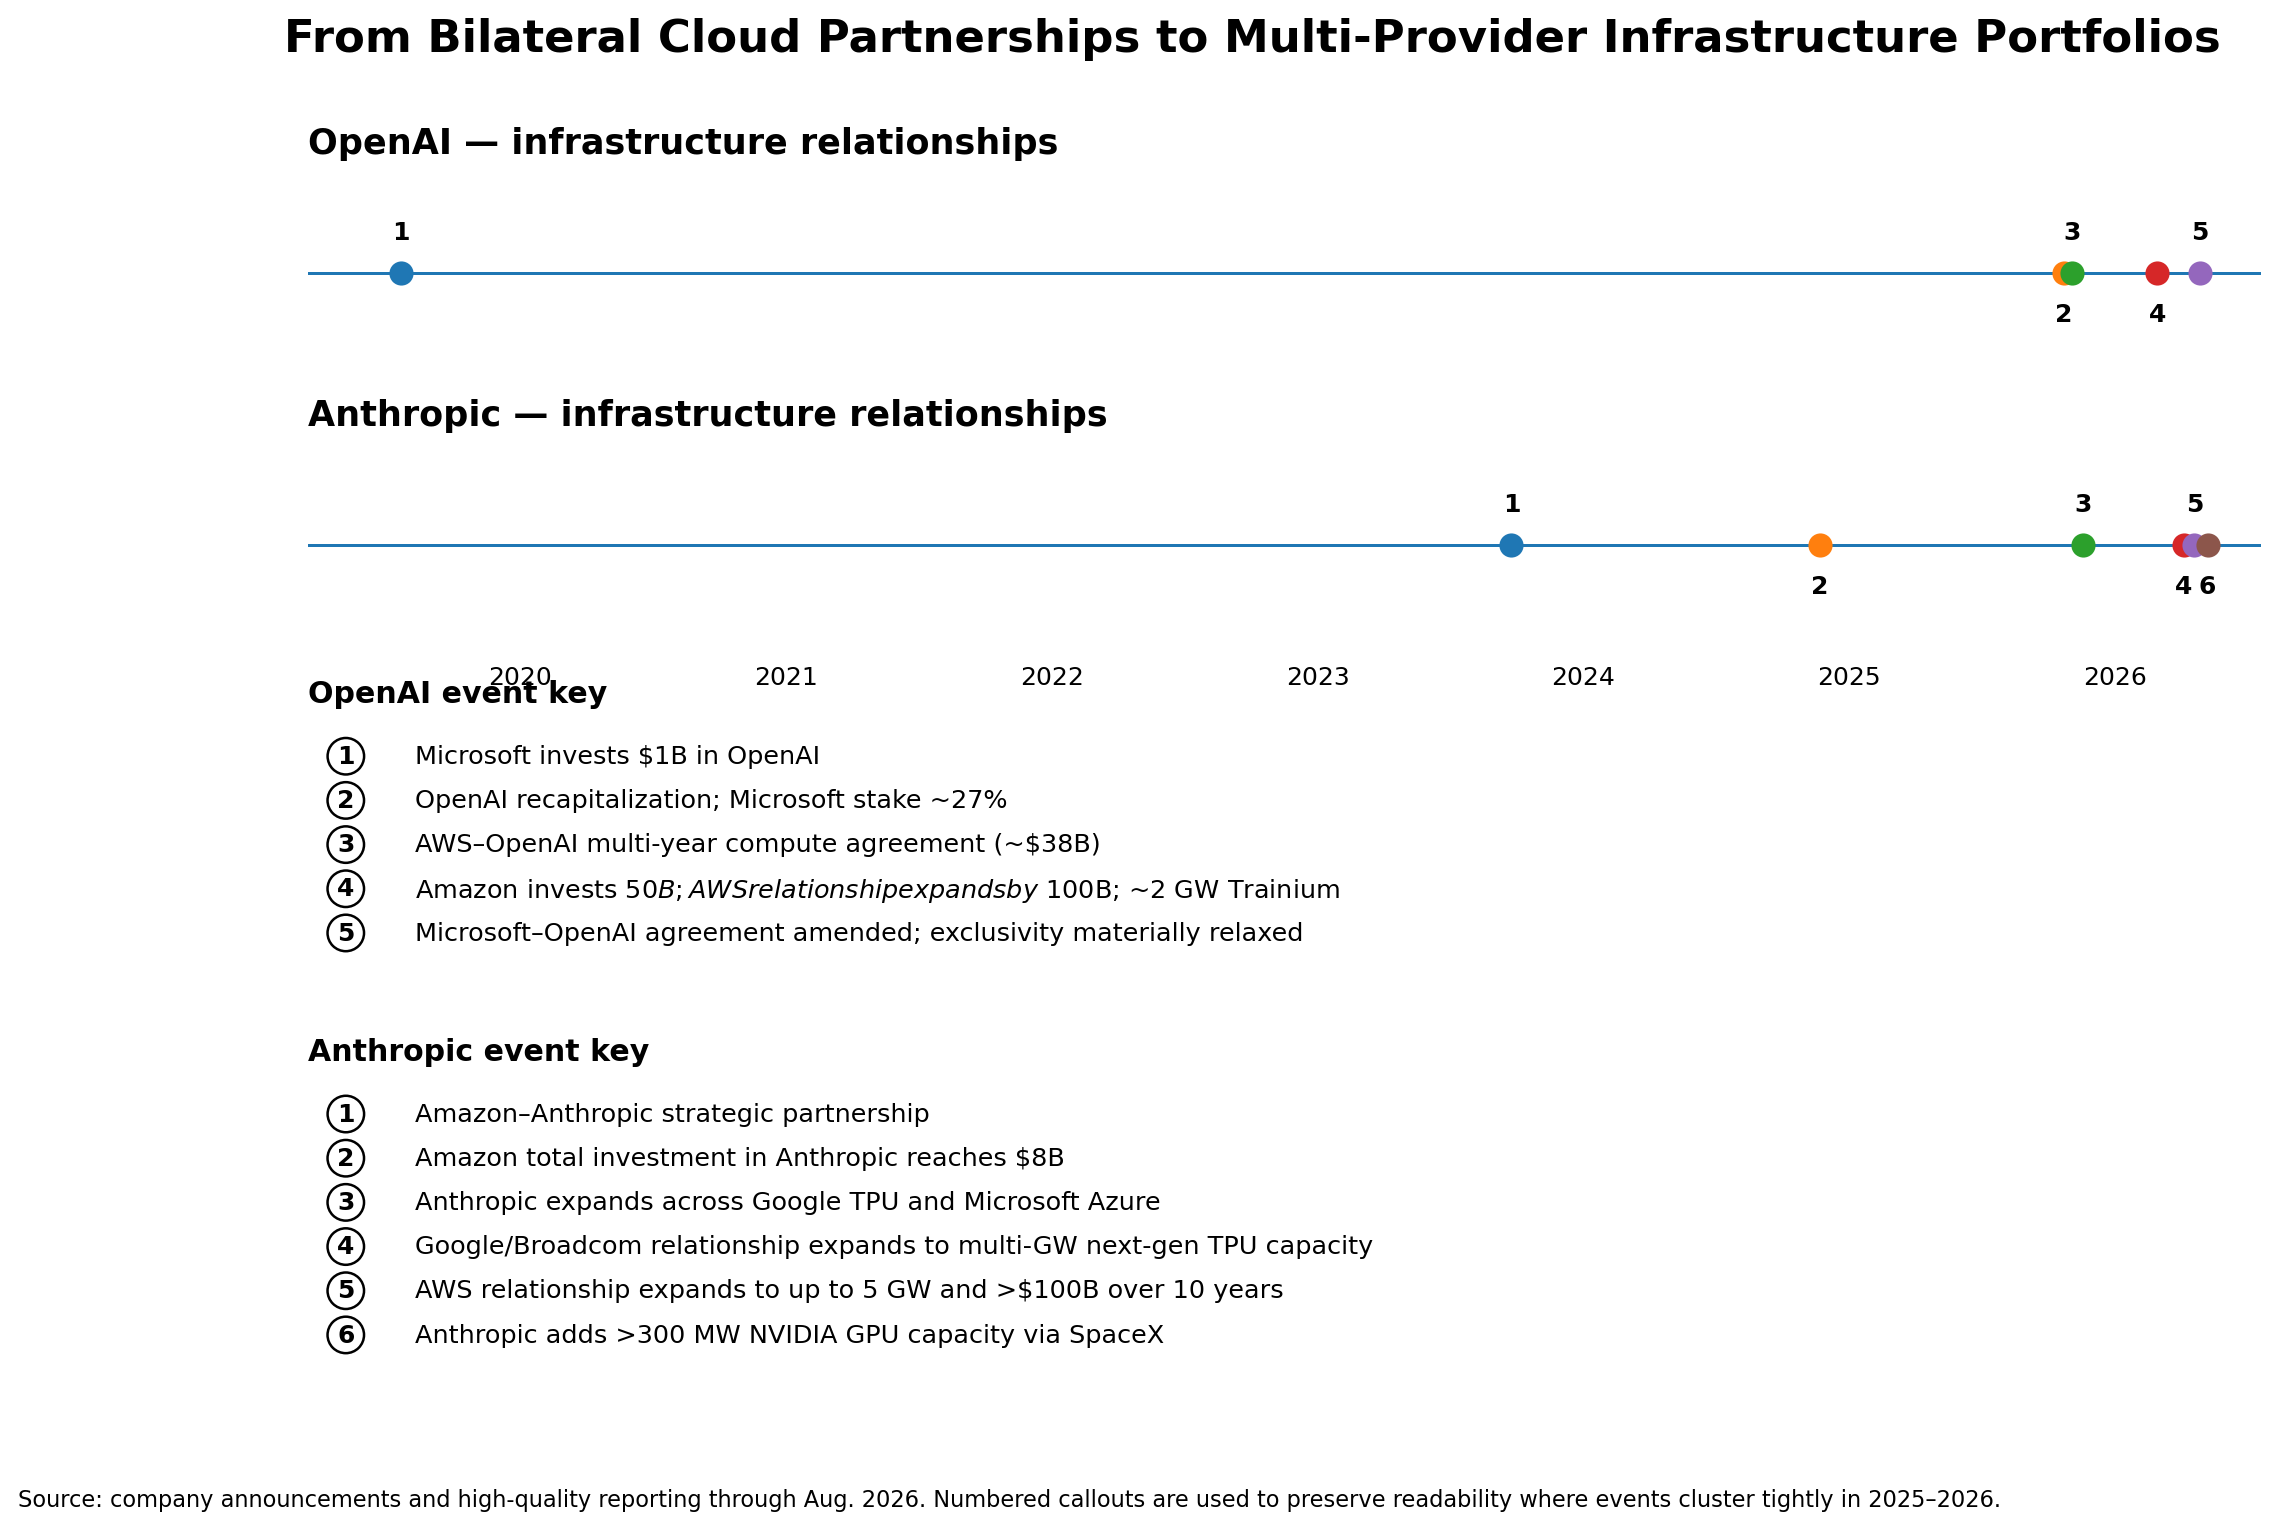
Exhibit 3 — From Bilateral Cloud Partnerships to Multi-Provider Infrastructure Portfolios

The chronology shows the strategic shift from relatively concentrated bilateral relationships toward overlapping networks of capital, compute, and distribution.
Methodological Note

These exhibits are based on disclosed company announcements and high-quality reporting available through August 20, 2026. They intentionally avoid converting unlike commitments into a single headline value. Gigawatts describe capacity; dollars describe investments or contractual purchase obligations; neither is equivalent to realized utilization or economic value. Where terms are described as “up to,” the chart retains that qualification in the underlying analysis.
Etched: The $21 Billion Bet on Specialized AI Inference

What a $700 million financing round reveals about the economics of inference, the limits of GPU generality, and the emerging contest to reshape AI infrastructure

Solten Deal Analysis 
Published / updated: August 20, 2026 
Research universe: AI Infrastructure / Semiconductors / Capital & Deals

Research Passport

Company: Etched
Headquarters: San Jose, California
Founded: 2022
Founders: Gavin Uberti, Robert Wachen, Chris Zhu

Transaction: $700 million financing
Announced valuation: $21 billion
Date announced: August 18, 2026
Lead investor: Jane Street
Other disclosed participants: Kleiner Perkins, Sequoia, Andreessen Horowitz, Tiger Global, Bain Capital Ventures, Neo, Primary, Stripes, Positive Sum, and Blackstone

Company-stated total funding: $1.9 billion
Evidence cut-off: August 20, 2026
Research type: Deal Analysis
Estimated reading time: ~35 minutes

Executive Summary


Etched’s latest financing is not interesting primarily because a three-year-old semiconductor company raised $700 million. It is interesting because investors are assigning a $21 billion value to a company whose commercial history is still extremely short, whose first customer rack was delivered only last month, whose publicly identified customer base remains minimal, and whose most important performance claims are not yet supported by broad independent benchmark evidence.


At the same time, dismissing the valuation as simple AI exuberance misses what investors may actually be underwriting. Etched sits at the intersection of several powerful structural forces: inference is becoming the dominant recurring compute burden in AI; model-serving economics increasingly depend on tokens per dollar and tokens per watt; hyperscalers and model labs are actively seeking alternatives to a single-vendor GPU stack; and the AI infrastructure market is beginning to reward systems designed around specific workload economics rather than general-purpose programmability.


The company has also changed materially. In 2024 Etched publicly presented itself as a radical transformer-only ASIC company. The proposition was intentionally narrow: hardwire the dominant model architecture into silicon and sacrifice generality for extraordinary efficiency. By mid-2026, Etched’s public positioning had broadened into “frontier inference clusters” — co-designed chips, memory, interconnect, racks, cooling, software and manufacturing. Its current materials emphasize Low Voltage Inference and Cluster Scale Memory, and the company says its systems can run large mixture-of-experts and non-transformer designs. That evolution reduces one of the original thesis risks, but also means the company should no longer be analyzed simply as “the transformer ASIC startup.”


The current round contains an unusually strong strategic signal: Jane Street is simultaneously the lead investor and Etched’s first disclosed customer. Jane Street says it tested the chip, received the first rack in July and is deploying it in production workloads. This matters because Jane Street is not a passive financial sponsor. Earlier in 2026 it committed approximately $6 billion to CoreWeave for AI cloud capacity and invested $1 billion in CoreWeave equity. Its investment in Etched is therefore consistent with a broader strategy of controlling access to high-performance compute for latency- and research-intensive workloads.


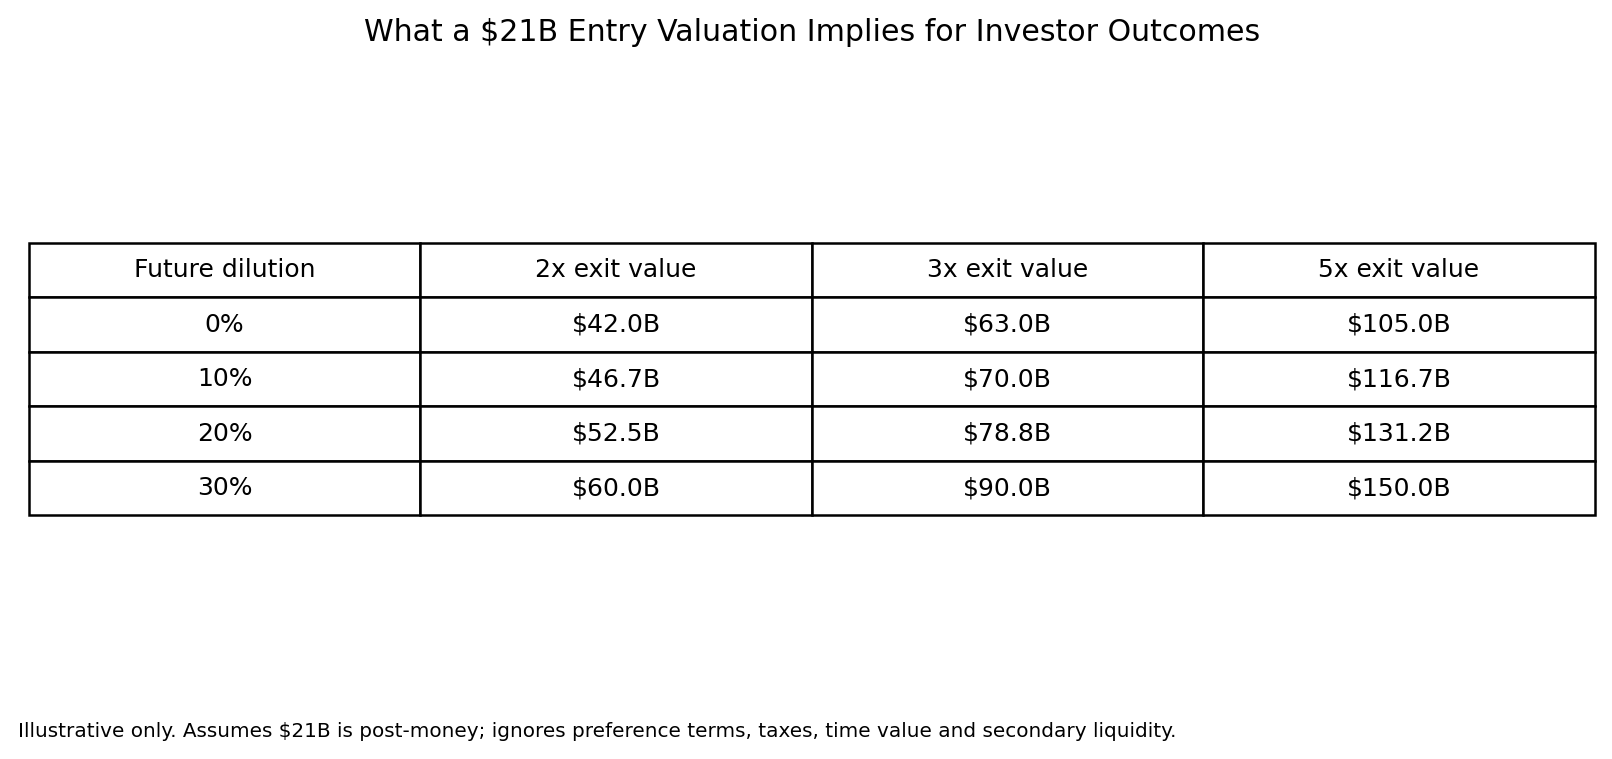
The central valuation question is severe. A $21 billion entry valuation means that, before accounting for future dilution or preference terms, investors need an eventual company value of roughly $42 billion for 2x, $63 billion for 3x and $105 billion for 5x. If Etched experiences 20% future dilution, those thresholds rise to roughly $52.5 billion, $78.8 billion and $131.3 billion. This is not impossible in a market as large as AI infrastructure, but it requires Etched to become much more than a successful chip startup. It likely requires the company to establish a durable platform position in large-scale inference, capture significant system-level economics, and survive successive NVIDIA and hyperscaler product cycles.


The strongest Solten & Co. interpretation is that the Etched round is an early institutional bet on a market structure in which inference fragments away from a universal GPU architecture. The strongest counter-thesis is that NVIDIA’s software ecosystem, scale, systems integration, pace of product improvement and financing power continue to compress the available window for specialized challengers faster than Etched can convert technical advantage into a durable commercial moat.


Key Findings


  1. The $700 million round is best understood as a bet on the future structure of inference, not simply on one chip. Etched is attempting to own an integrated inference system spanning silicon, memory, interconnect, racks, cooling, software and production.


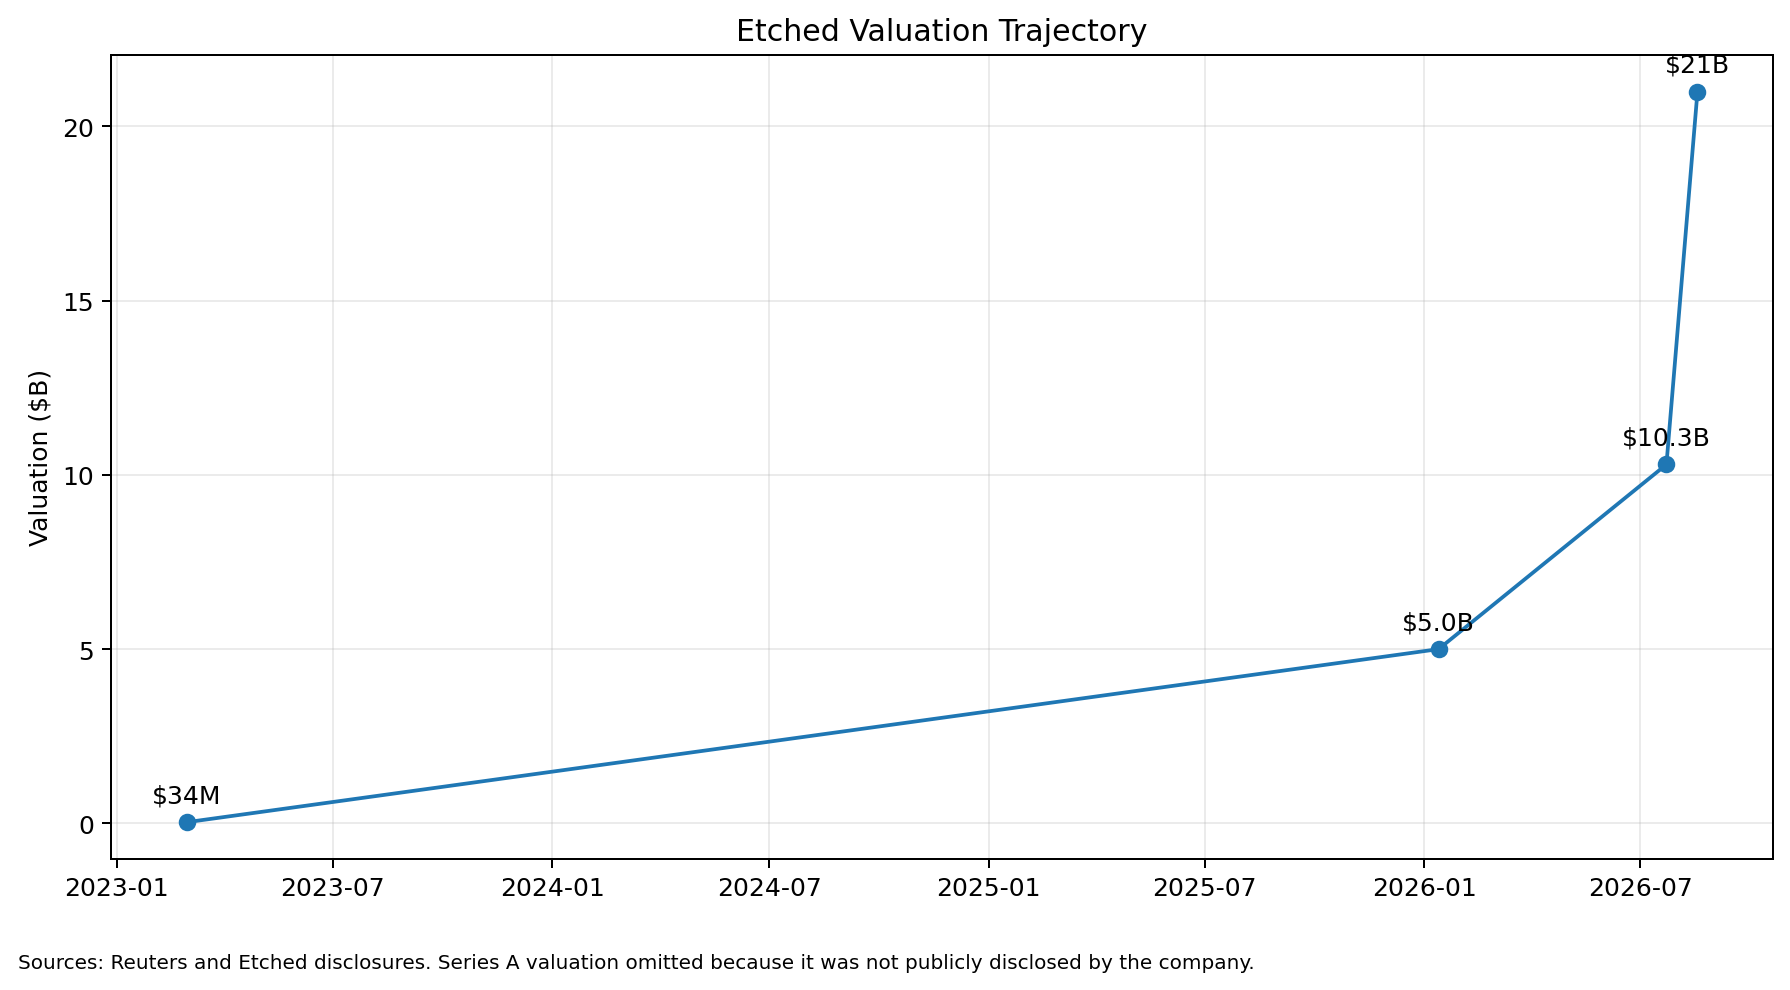
  1. The valuation has moved much faster than publicly demonstrated commercial maturity. Etched went from a reported $5 billion post-money valuation in December 2025 to $10.3 billion in July 2026 and $21 billion in August 2026. The latest valuation more than doubled in less than one month.


  1. Jane Street is the most strategically important participant in the round because it is both lead investor and first disclosed customer. That dual role provides stronger demand validation than a conventional venture syndicate, but also introduces concentration and signaling questions.


  1. The company’s “more than $1 billion in customer contracts” is meaningful evidence of demand, but it is not equivalent to recognized revenue, recurring revenue or even necessarily fully binding backlog. Public disclosure remains insufficient to determine contract quality, customer concentration, delivery schedules or gross-margin economics.


  1. Etched’s product thesis has broadened materially since 2024. The original transformer-only framing exposed the company to architecture obsolescence. The 2026 system is presented as a broader inference platform using Low Voltage Inference and Cluster Scale Memory and is said to run MoE and non-transformer designs.


  1. NVIDIA remains the reference competitor, but Etched’s real competitive set is wider: NVIDIA, AMD, Google TPU, AWS Trainium, Microsoft Maia, Meta MTIA, Cerebras and other specialized inference architectures. The market is evolving toward heterogeneous compute rather than a simple NVIDIA-versus-startup contest.


  1. The deal is strategically important for the semiconductor ecosystem because success would validate a merchant specialized-inference business model distinct from both general-purpose GPUs and vertically integrated hyperscaler ASICs.


  1. The most important unresolved question is no longer whether Etched can produce working silicon. It can. The question is whether it can repeatedly manufacture, deploy and support systems at scale while delivering independently verifiable cost, latency and power advantages after software, networking, utilization and customer migration costs are included.


Table of Contents


Executive Summary

Key Findings

Why This Deal Matters

Scope & Methodology

The Company: From Transformer ASIC to Frontier Inference Systems

What Etched Actually Builds

Manufacturing and Production Strategy

Commercial Evidence: $1 Billion in Contracts Is Not $1 Billion in Revenue

Jane Street: Why the Lead Investor Matters

Financing History

Current Transaction Anatomy

Valuation: What Must Be True at $21 Billion

The Investor Coalition

Competitive Landscape

Market Structure: The Inference Economy Is Becoming Its Own Industry

Industry Impact: First-, Second- and Third-Order Effects

Broader Economic Implications

Risks to Etched

Risks to Investors

Risks to the Industry

Scenario Analysis

Solten & Co. Thesis

Counter-Thesis

Falsification Criteria

Key Unknowns

What to Watch Next

Research Exhibits

Sources & Evidence

Methodological Note

About Solten & Co.


Scope & Methodology


Research question. This report asks what Etched’s August 2026 financing reveals about the company’s emerging business, the economics of specialized AI inference, investor expectations embedded in a $21 billion valuation, and the likely competitive effects on the broader AI infrastructure market.


Scope. The analysis covers Etched’s corporate history, product evolution, disclosed financing history, current investor coalition, customer evidence, valuation implications, competitive landscape, industry structure and potential first-, second- and third-order effects. It is not a full technical audit of Etched silicon and does not constitute an investment recommendation.


Evidence hierarchy. Priority is given to Etched disclosures, official investor and partner statements, SEC filings and other primary sources. Reuters, TechCrunch and other high-quality specialist reporting are used where private-company terms are not publicly disclosed. Academic accelerator research is used to test the general validity of performance comparisons.


Evidence cut-off. August 20, 2026.


Material limitations. Etched is private. Detailed financial statements, cap-table data, preferred-stock terms, production yields, customer contracts, pricing, gross margins and normalized third-party benchmark results are not publicly available. Therefore ownership, return and valuation analyses are explicitly illustrative where required.


Evidence classes. DISCLOSED FACT identifies primary-source facts. REPORTED TERM identifies credible but externally reported information. ESTIMATE identifies calculations based on incomplete public data. SOLTEN & CO. INTERPRETATION identifies analytical synthesis.


What Changed


Etched is no longer best understood through its original 2024 description as a transformer-only chip company. Its public 2026 strategy has moved upward in the stack toward complete frontier inference systems and toward a broader architecture story built around Low Voltage Inference and Cluster Scale Memory. The company now says its systems are running massive MoE models and non-transformer designs.


The commercial evidence has also changed. In June, the company had working silicon and more than $1 billion in customer contracts but no disclosed production customer. By August, Jane Street had received the first rack and was actively deploying it. This materially improves the evidence base, although it does not resolve questions around normalized performance, contract quality, revenue conversion or margins.


The financing context changed just as quickly. Etched’s valuation moved from $5 billion in the financing disclosed for December 2025 to $10.3 billion in July 2026 and $21 billion in August. The market is therefore not merely rewarding technical execution; it is rapidly capitalizing an expected future position in the inference value chain.


Why This Deal Matters


Etched announced on August 18 that it had raised $700 million at a $21 billion valuation in a round led by Jane Street. The company said the financing included Kleiner Perkins, Sequoia, Andreessen Horowitz, Tiger Global, Bain Capital Ventures, Neo, Primary, Stripes, Positive Sum and Blackstone. It also disclosed that Jane Street was its first customer, had received the company’s first shipped rack in July and was actively deploying the system.


This financing deserves attention for three reasons.


First, the speed of valuation expansion is extreme even by current AI standards. Etched was valued at $10.3 billion in a $300 million Series C announced July 23. Less than four weeks later, the valuation was $21 billion. That is approximately a 104% increase in headline valuation in 26 days.


Second, the round arrives at the moment Etched is crossing the line from technical promise to commercial execution. The company emerged from stealth in June with working A0 silicon on TSMC N4P, a team of more than 400, over $1 billion in customer contracts and a plan to ship its first racks during the summer. By August, the first disclosed rack had reached Jane Street. The investment therefore prices not merely a design concept but a very early production system.


Third, the deal tests a larger industry hypothesis: whether the economics of AI inference are now large enough to support highly specialized merchant hardware companies alongside GPUs and hyperscaler custom silicon.


The Company: From Transformer ASIC to Frontier Inference Systems


Etched was founded in 2022 by Gavin Uberti, Robert Wachen and Chris Zhu, three Harvard dropouts who later became Thiel Fellows. Early reporting described Uberti and Zhu as the technical founders; by 2024, Primary Venture Partners publicly described all three as co-founders.


Uberti’s background includes compiler work and development of a Cortex-M backend for TVM. Zhu has a mathematics and high-performance-computing background. Wachen’s role has been more commercially oriented. Etched’s current leadership team has been deliberately built around experienced semiconductor operators, including former Cypress CTO Mark Ross, former NVIDIA platform leader Brian Loiler, former NVIDIA/Auradine architect Saptadeep Pal, former Google TPU software leader David Munday and production executives with experience in high-volume consumer hardware.


This composition matters because semiconductor startups often fail not at architecture design but at production, packaging, supply, system validation, developer tooling and customer deployment. Etched’s hiring strategy appears designed to close precisely that execution gap.


The original product thesis was unusually simple and unusually risky. In 2024 the company described Sohu as an ASIC designed specifically for transformer inference. CEO Gavin Uberti openly acknowledged the binary nature of the bet: if transformers disappeared, the company’s original architecture would be impaired; if they remained dominant, specialization could create a major performance advantage.


By 2026, however, the public product definition had changed. Etched no longer leads with Sohu or with a “transformer-only” identity. Its current category is “frontier inference clusters.” The company says it co-designs chips, racks, software and manufacturing methods to optimize throughput, latency, cost and power efficiency across both prefill and decode workloads.


That shift is strategically significant. It suggests Etched is moving from an architecture-specific chip thesis to a system-level inference thesis.


What Etched Actually Builds


Etched’s current system claims two central technical differentiators.


Low Voltage Inference (LVI). Etched argues that conventional AI chips cannot sustain peak floating-point throughput because power draw and thermal limits force clock reductions. Its architecture is designed to run math blocks at materially lower voltage, allowing higher compute density within a fixed power envelope. The company says this enables large sparse mixture-of-experts models to operate at over 80% of peak FLOPS without thermal throttling.


Cluster Scale Memory (CSM). Etched argues that decode workloads are frequently constrained by memory access and inter-chip communication rather than raw FLOPS. Its system combines HBM and SRAM with a proprietary interconnect to create a lower-latency shared memory pool across a scale-up domain. The intended effect is to reduce the trade-off between high-capacity HBM systems and very fast but capacity-limited SRAM-centric designs.


These are company claims, not independent performance conclusions. The company has not yet published a broad third-party benchmark suite that allows investors to normalize performance across batch size, context length, model architecture, precision, concurrency, power, rack configuration and software stack.


That absence is currently one of the most important analytical constraints.


Independent academic work on AI accelerators reinforces why such normalization matters. A 2026 comparative study of NVIDIA, AMD, Cerebras, SambaNova, Gaudi and TPU systems found that the optimal hardware platform varies significantly with model size, sequence length, batch size and workload characteristics. It also found that high utilization is critical to realizing energy-efficiency benefits. A headline tokens-per-second figure therefore does not by itself establish superior production economics.


Manufacturing and Production Strategy


Etched’s first A0 silicon returned from TSMC on the N4P process in early 2026. The company says it achieved first-pass silicon success in under three years from its seed round.


It has also chosen a higher degree of operational integration than many fabless semiconductor startups. Etched says it has opened a Taiwan factory, built a data center, test house and NPI prototyping lab in San Jose, and opened an approximately 80,000-square-foot facility near its headquarters to accelerate production and prototyping. It describes “production is the product” as an operating principle.


This strategy has two interpretations.


The positive interpretation is that Etched understands the commercialization bottleneck. A custom AI accelerator is not useful merely because the chip works. Customers buy complete systems, qualification, networking, thermals, firmware, software and reliable supply. Vertical integration may let Etched iterate faster and reduce the hand-offs that slow traditional semiconductor development.


The counterpoint is capital intensity. Bringing more system design, validation and manufacturing processes inside the company increases fixed costs, working-capital needs and organizational complexity. The $700 million round therefore appears partly designed to finance an industrial scaling problem, not just semiconductor R&D.


Commercial Evidence: $1 Billion in Contracts Is Not $1 Billion in Revenue


Etched says it has secured more than $1 billion in customer contracts across public and private frontier AI companies and cloud providers. The current announcement adds one major validation point: Jane Street is now a named customer with a rack physically deployed.


This is meaningful progress. In June, outside reporting correctly noted that Etched had not publicly named customers, disclosed contract terms or provided independent performance benchmarks. By August, one customer had moved from anonymous demand to actual deployment.


But the public data still leave major diligence gaps.


We do not know:


  • how much of the $1 billion is binding purchase commitments versus reservations, milestones or conditional orders;
  • how concentrated the contracts are among a small number of customers;
  • the delivery schedule;
  • cancellation rights;
  • gross margin on initial systems;
  • recognized revenue to date;
  • how much revenue depends on customer acceptance testing;
  • whether contracts cover chips, racks, services or future generations;
  • how much capital Etched must spend before it can recognize the contracted revenue.


This distinction is critical because the company’s $21 billion valuation is roughly 21 times the headline $1 billion contract figure. That is not a revenue multiple. It should not be treated as one.


The correct interpretation is that investors are valuing expected future economics far beyond currently disclosed commercial realization.


Jane Street: Why the Lead Investor Matters


Jane Street is unusually important to the Etched story.


It is not simply a hedge fund or a venture investor adding an AI hardware position. Jane Street is one of the world’s most technology-intensive trading firms. Its core business rewards extremely high-performance research and computation, and it has become a major direct buyer of AI infrastructure.


In April 2026, Jane Street committed approximately $6 billion to CoreWeave for AI cloud capacity across multiple facilities, including NVIDIA Vera Rubin technology, and separately invested $1 billion in CoreWeave equity. Reuters described the transaction as part of Jane Street’s broader effort to scale machine learning across its global markets research.


That makes Jane Street’s Etched investment much more informative than a conventional VC endorsement. Jane Street has access to NVIDIA-based infrastructure through CoreWeave, has the technical capacity to evaluate alternatives, and has an economic incentive to improve inference performance for highly latency-sensitive and compute-intensive workloads.


According to Etched, Jane Street tested the chip before leading the round and is now running a rack in its own data center.


This creates a powerful proof point — but it also requires analytical caution.


Jane Street is simultaneously customer, investor and signal provider. Those roles can reinforce each other. A customer that owns equity may tolerate early product friction or adopt infrastructure partly because it expects strategic upside. Conversely, the fact that Jane Street already has access to large-scale NVIDIA systems makes its decision to deploy Etched more significant, not less.


The most useful conclusion is therefore not “Jane Street proves Etched wins.” It is that a technically sophisticated, capital-rich buyer with access to alternative infrastructure believes Etched is sufficiently credible to test in production and sufficiently valuable to lead a major financing.


Financing History


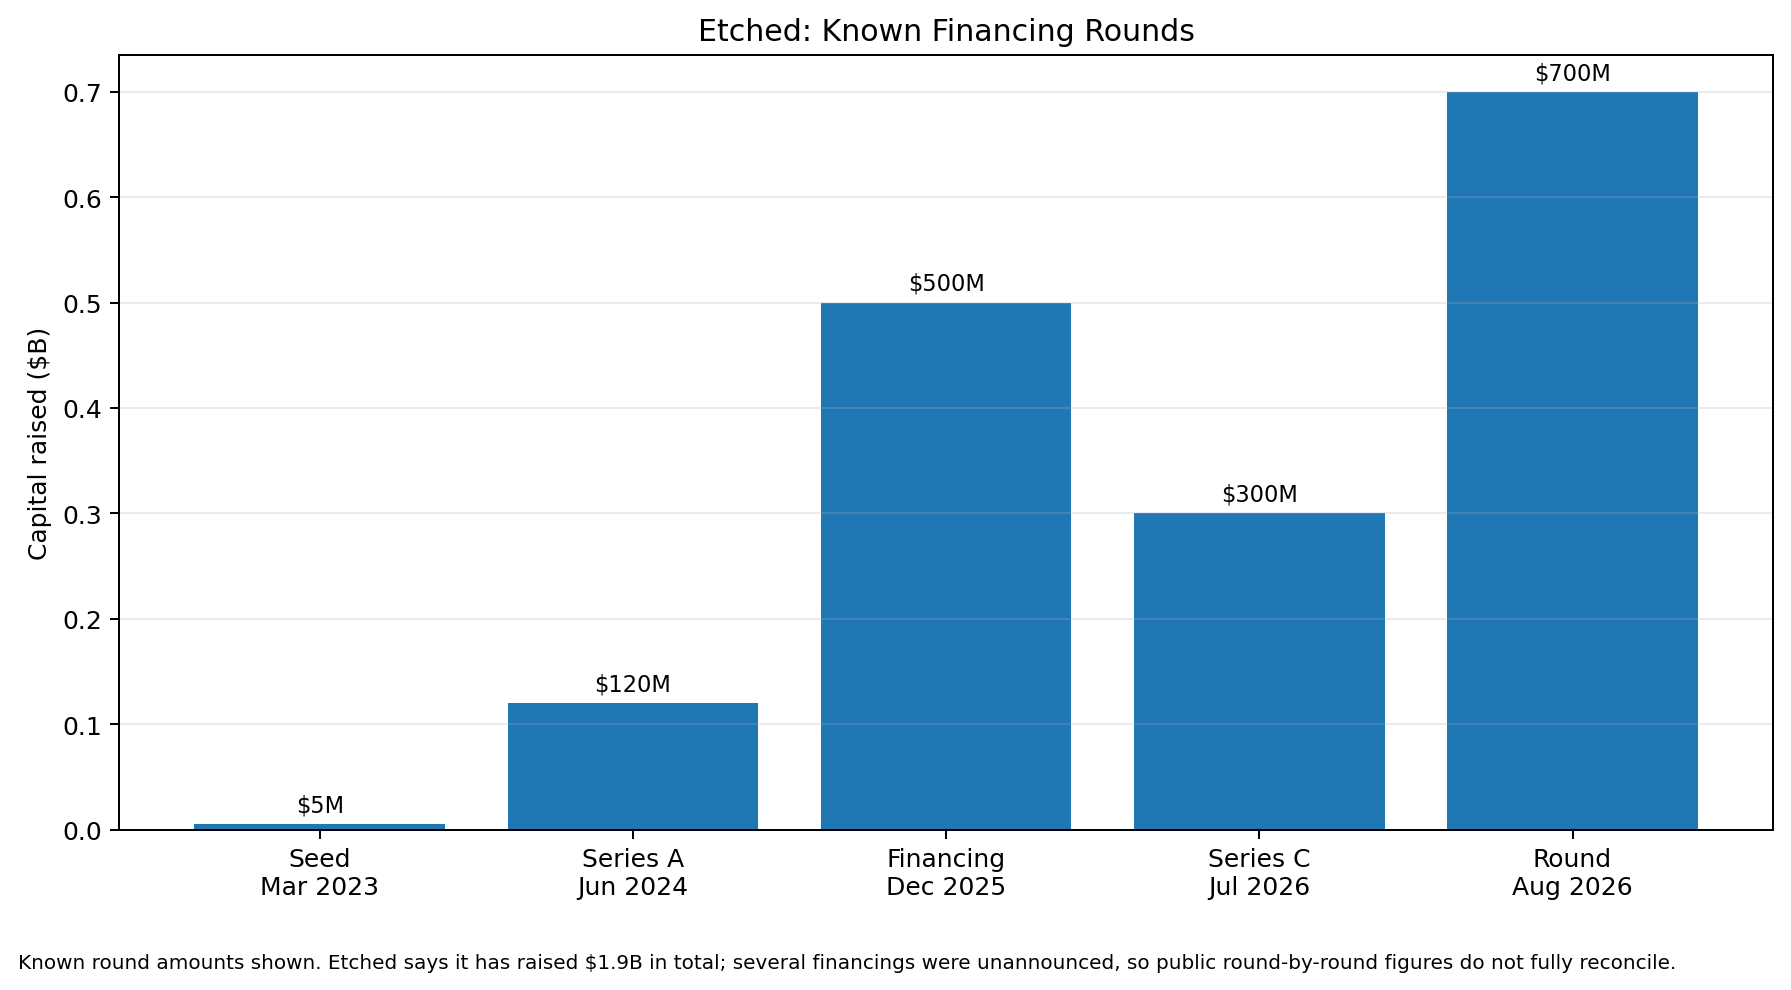
March 2023 — Seed

Etched raised approximately $5.4 million at a reported $34 million valuation. Reuters later confirmed the valuation when covering the Series A.


June 2024 — Series A

Etched raised $120 million, co-led by Primary Venture Partners and Positive Sum. The round included Peter Thiel and a long list of technology founders and investors. The company said the capital would support chip development and manufacturing. A company-level valuation was not publicly disclosed at the time.


December 2025 / disclosed June 2026 — $500 million financing

When Etched emerged from stealth, it disclosed that its latest prior financing had been $500 million at a $5 billion post-money valuation. It also said it had raised $800 million across multiple unannounced financings by that point.


July 23, 2026 — Series C

Etched raised $300 million at a $10.3 billion valuation. Sequoia led, with Andreessen Horowitz, Jane Street, Diffusion and SK Hynix among participants. The company said proceeds would accelerate production and customer deployments.


August 18, 2026 — $700 million round

Jane Street led at a $21 billion valuation, joined by Kleiner Perkins, Sequoia, Andreessen Horowitz, Tiger Global, Bain Capital Ventures, Neo, Primary, Stripes, Positive Sum and Blackstone.


Etched’s current announcement says the company has raised $1.9 billion in total. Publicly identifiable round amounts do not reconcile perfectly to that figure because several financings were never individually announced and historical totals were rounded. This is a useful example of why venture funding databases should not be treated as primary evidence when the company itself describes undisclosed rounds.


Current Transaction Anatomy


DISCLOSED FACT: Etched raised $700 million at a $21 billion valuation.


DISCLOSED FACT: Jane Street led the round.


DISCLOSED FACT: Kleiner Perkins, Sequoia, Andreessen Horowitz, Tiger Global, Bain Capital Ventures, Neo, Primary, Stripes, Positive Sum and Blackstone participated.


UNKNOWN: Whether the $21 billion figure is explicitly pre-money or post-money in the legal financing documents. Public coverage generally presents it as the round valuation without disclosing the security terms.


UNKNOWN: Secondary component, if any.


UNKNOWN: Liquidation preference, participation rights, anti-dilution protection, board rights and other preferred-stock terms.


ESTIMATE: If $21 billion is a post-money valuation and the entire $700 million is primary equity, the round would represent approximately 3.3% of post-money ownership before other option-pool or security effects. This is only an illustrative estimate and should not be treated as a disclosed cap-table fact.


The striking point is that Etched is raising large absolute amounts with relatively modest headline dilution because valuation has accelerated so quickly.


Valuation: What Must Be True at $21 Billion


A $21 billion private valuation changes the analytical standard. At this level, the central question is no longer whether Etched can become a meaningful semiconductor company. It is whether Etched can become a very large infrastructure platform.


Ignoring future dilution, new investors require approximately:


  • $42 billion eventual equity value for a 2x gross multiple;
  • $63 billion for 3x;
  • $105 billion for 5x.


With 20% future dilution, the required exit values increase to approximately:


  • $52.5 billion for 2x;
  • $78.8 billion for 3x;
  • $131.3 billion for 5x.


Those values are possible only if Etched reaches a scale comparable with major public semiconductor or infrastructure companies.


Because current recognized revenue is not publicly disclosed, conventional revenue-multiple analysis is impossible. The $1 billion-plus contract figure is insufficient because contract value, recognized revenue, gross margin and duration are unknown.


A more useful valuation framework is therefore milestone-based.


To support the current valuation, Etched likely needs to demonstrate several of the following simultaneously:


  1. Production-scale reliability across multiple customers.
  2. Independent evidence of superior total cost of ownership on important frontier inference workloads.
  3. A software and deployment layer that makes migration materially easier than adopting a typical custom ASIC.
  4. Multi-generation product execution, not a single architecture win.
  5. A sufficiently large customer base to prevent Jane Street or any one AI lab from dominating revenue.
  6. Gross margins consistent with attractive merchant semiconductor or integrated-system economics.
  7. Access to foundry, advanced packaging and memory supply at scale.
  8. Continued relevance as model architectures evolve.
  9. A market large enough for both hyperscaler custom silicon and merchant specialized systems.
  10. Evidence that NVIDIA cannot eliminate Etched’s cost/performance advantage through rapid platform iteration or pricing.


The Investor Coalition


The syndicate tells its own story.


Jane Street brings customer validation and direct experience buying large-scale compute.


Sequoia led the July Series C and returned immediately in the August financing. Its follow-on participation is a strong signal of continued conviction after receiving access to non-public diligence during the prior round.


Andreessen Horowitz is another repeat investor, reinforcing the view that Etched is being underwritten as a major AI infrastructure platform rather than a conventional semiconductor startup.


Kleiner Perkins is notable because its managing partner publicly framed the opportunity around inference economics — specifically tokens per dollar and tokens per watt. The firm also has exposure across AI labs and infrastructure companies, giving it a broad view of demand.


SK Hynix, which participated in the July round, is strategically relevant as a major memory supplier even though it was not named in the August investor list. Its presence in the cap table illustrates how Etched’s financing network intersects with the semiconductor supply chain.


VentureTech Alliance, a fund linked to the semiconductor ecosystem and disclosed in earlier financings, further deepens the strategic investor layer.


The broader coalition — Blackstone, Tiger Global, Bain Capital Ventures, trading firms and major technology angels — suggests that Etched has moved beyond early venture financing into crossover-style capital formation.


Competitive Landscape


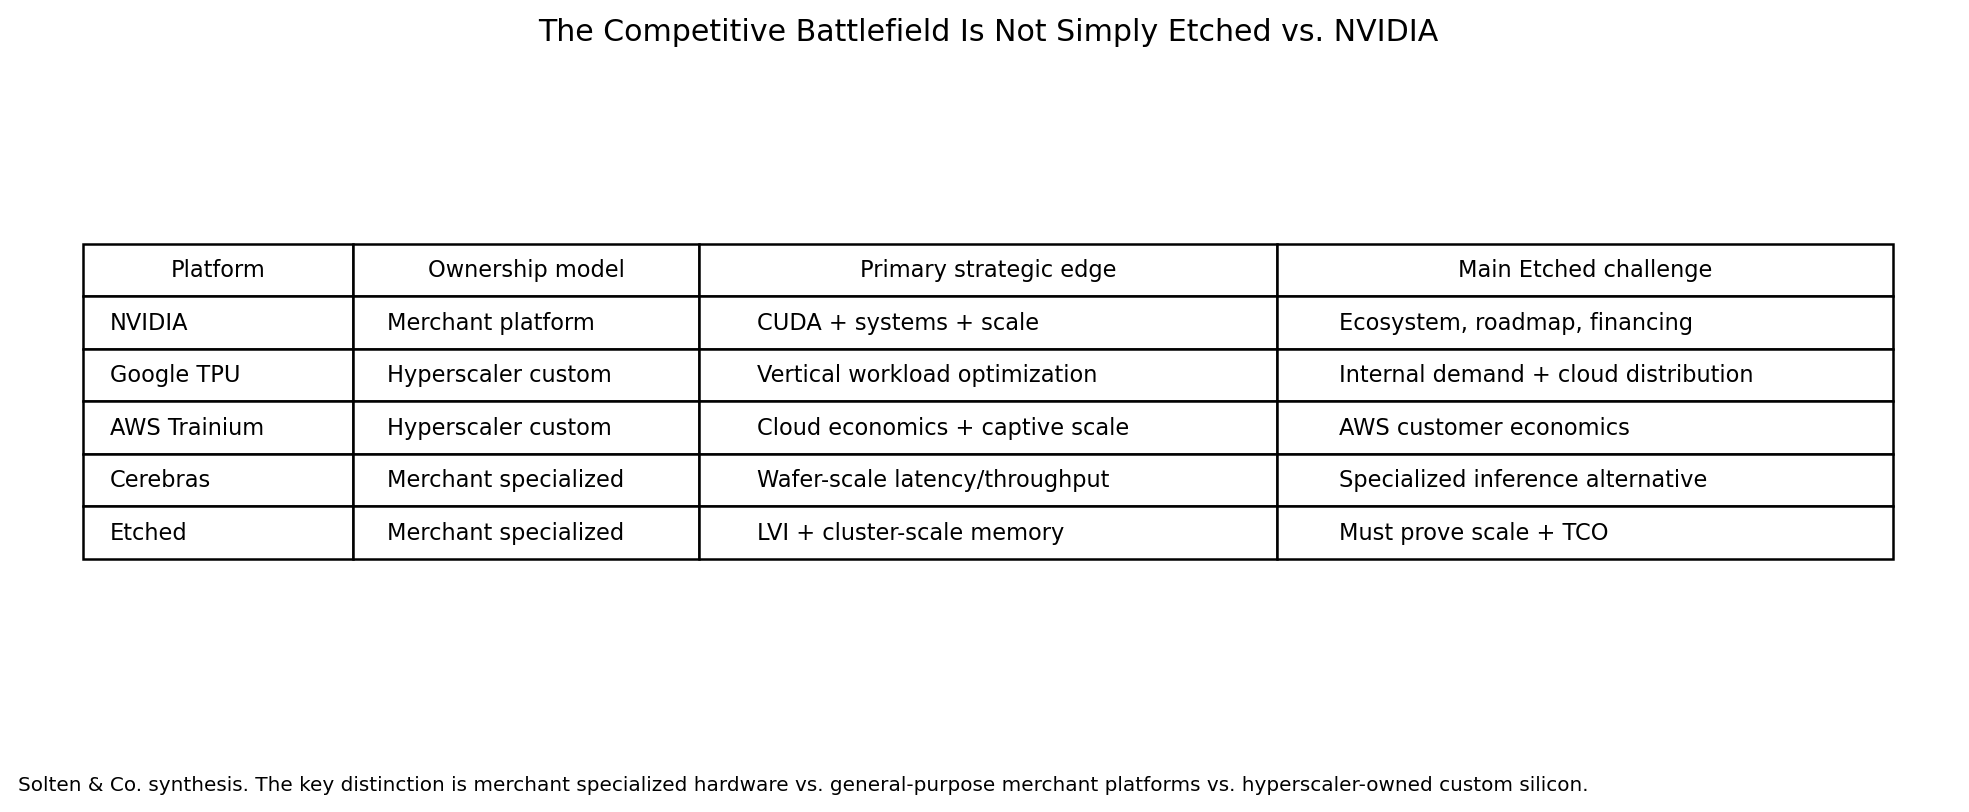
Exhibit 4 — The Competitive Battlefield Is Not Simply Etched vs. NVIDIA

This framework separates merchant general-purpose platforms, hyperscaler-owned custom silicon and merchant specialized architectures. Etched’s strategic opening exists only if a meaningful customer segment wants hyperscaler-like specialization without owning a hyperscaler-scale internal silicon program.


The lazy framing is “Etched versus NVIDIA.” The real market is more complicated.


NVIDIA remains the dominant reference platform because it combines high-performance accelerators with CUDA, networking, systems, enterprise software, developer tooling, financing relationships and an enormous installed base. NVIDIA reported fiscal 2026 revenue of approximately $216 billion, with data-center growth driven by AI. Its gross margins remain above 70%, which demonstrates the economic value of platform control.


But NVIDIA is facing competition from several directions.


Hyperscaler custom silicon. Google TPUs, AWS Trainium, Microsoft Maia and Meta MTIA are increasingly important because the largest buyers have enough workload volume to justify architecture-specific optimization. Google and Broadcom have extended TPU collaboration through 2031, and Google is expanding external TPU distribution. AWS has made Trainium central to major OpenAI and Anthropic compute relationships.


Merchant accelerators. AMD remains the largest conventional GPU alternative. Cerebras uses wafer-scale processors and is explicitly targeting fast inference. Its newly announced CS-4 system illustrates how quickly the specialized-inference market is moving.


Specialized architectures. Groq demonstrated demand for low-latency inference and ultimately entered a major technology relationship with NVIDIA, a reminder that incumbent responses can include acquisition, licensing and ecosystem absorption rather than only price competition.


Other startups and new architectures. Tenstorrent, SambaNova, d-Matrix, Furiosa and others continue to pursue different combinations of programmability, memory architecture, inference efficiency and system design.


Etched is therefore competing on multiple dimensions:


  • tokens per dollar;
  • tokens per watt;
  • latency;
  • throughput;
  • programmability;
  • model compatibility;
  • memory capacity and bandwidth;
  • interconnect performance;
  • rack-level deployment complexity;
  • supply availability;
  • software maturity;
  • customer switching cost;
  • production scale.


The important market question is not whether one architecture wins universally. Independent accelerator research increasingly suggests that workload characteristics determine the optimal hardware. The likely market structure is heterogeneous.


Etched’s opportunity is to own a sufficiently valuable portion of that heterogeneity.


Market Structure: The Inference Economy Is Becoming Its Own Industry


The shift from training to inference is central to the Etched thesis.


Training creates frontier capability, but inference monetizes that capability. Every user query, coding-agent step, enterprise workflow and autonomous tool call creates recurring inference demand. As agentic systems perform longer reasoning chains and call other models or software repeatedly, the number of inference operations per unit of useful work can rise dramatically.


NVIDIA itself now describes inference as the dominant AI workload. The company’s fiscal 2026 annual materials state that inference has overtaken training as the primary workload and emphasize the changing economics of AI as models move into large-scale use.


This shift matters because inference rewards different optimization choices than training.


Training values flexibility, enormous distributed scale and rapid support for new model operations.


Inference can reward specialization when workloads are repeated at high volume. Once a model architecture is stable enough, purpose-built silicon can theoretically remove general-purpose overhead and optimize memory, scheduling and power around the real workload.


That creates a structural opening for companies like Etched.


But the same economics also motivate every hyperscaler to build custom silicon internally. Etched must therefore prove that a merchant specialized platform can compete not only with NVIDIA but with customers’ own chips.


Industry Impact: First-, Second- and Third-Order Effects


First-order effect: more credible competition in inference accelerators.


A working Etched system with a production customer increases pressure on NVIDIA and other accelerator vendors to compete on inference-specific economics rather than only headline training performance. It also gives AI labs and cloud providers another procurement option.


Second-order effect: greater bargaining power for large compute buyers.


Even if Etched never takes dominant market share, credible alternatives can influence NVIDIA pricing, supply terms and roadmap priorities. Large buyers gain leverage when they can move marginal inference workloads to specialized systems.


Second-order effect: more fragmentation in the software stack.


Every new accelerator creates integration cost. Model runtimes, compilers, kernels, observability, orchestration and deployment tooling must support heterogeneous systems. This creates opportunity for software layers that abstract hardware differences — but also raises switching costs for customers.


Second-order effect: more pressure on custom silicon economics.


If Etched can offer hyperscaler-like specialization without requiring a customer to design its own chip, it creates a new strategic option between buying NVIDIA and building an internal ASIC program.


Third-order effect: semiconductor value may shift from chips toward integrated inference systems.


Etched’s own evolution suggests that the economic unit is moving upward from the accelerator die to the rack or cluster. Memory, networking, cooling, power delivery, software and manufacturing become part of competitive differentiation.


Third-order effect: capital intensity spreads downstream.


If specialized inference becomes a major infrastructure category, large venture-funded companies may need hundreds of millions or billions of dollars to finance fabrication, inventory, systems and customer deployments before revenue scales. The distinction between venture capital and industrial project finance begins to blur.


Broader Economic Implications


Etched is one small company relative to the global semiconductor market, so macro claims should be restrained. But the financing contributes to several larger patterns.


AI is becoming more industrial. Capital is flowing not only into software but into fabs, packaging, memory, data centers, power, cooling, networking and purpose-built systems.


Inference efficiency has downstream economic significance. If specialized hardware materially lowers the cost per useful token, then applications that are currently uneconomic can become viable. That can affect pricing for AI software, enterprise automation and agentic workloads.


Hardware competition may also shift capital allocation. The stronger the evidence that inference supports multiple architectures, the more venture and growth capital may move toward specialized silicon, memory systems, networking and infrastructure software.


At the same time, the market risks overinvestment. High private valuations and massive compute commitments can create excess capacity if model monetization fails to scale at the pace assumed by infrastructure investors.


Risks to Etched


Technology risk. Performance claims may narrow under independent testing or production conditions. Different workloads may reduce the theoretical advantage of specialization.


Architecture risk. Although Etched’s 2026 system appears broader than the original transformer-only thesis, rapid changes in model architecture can still invalidate hardware assumptions.


Software risk. NVIDIA’s most durable moat is not only silicon. CUDA, libraries, tooling, developer familiarity and system integration create powerful switching costs.


Manufacturing risk. First-pass silicon is a major achievement but does not guarantee high-yield volume production across multiple generations.


Supply-chain risk. Etched depends on advanced foundry capacity, packaging, memory and other constrained semiconductor inputs.


Execution risk. Scaling from a few racks to gigawatt-scale deployments is an industrial challenge substantially harder than producing working A0 silicon.


Customer concentration risk. Only Jane Street is currently publicly identified. More than $1 billion in contracts could still be concentrated in a small number of counterparties.


Capital risk. Building inventory and production capacity may require further large financings before cash generation becomes self-sustaining.


Valuation risk. At $21 billion, execution disappointments can create severe private-market repricing even if the company remains technologically viable.


Incumbent-response risk. NVIDIA has the resources to respond through product acceleration, pricing, financing, software integration, partnerships or acquisition/licensing strategies.


Hyperscaler risk. The largest potential customers may prefer their own TPU, Trainium, Maia or MTIA systems rather than buying from a merchant startup.


Risks to Investors


The current round has unusually high expectations embedded in the entry price.


A successful product launch is not sufficient. Investors need Etched to sustain a major competitive position over multiple product generations.


Future dilution could materially raise required exit values. A capital-intensive company may need several more large rounds.


Private-market headline valuation does not disclose preference terms. Investors entering at different rounds may have very different downside protection.


The customer-investor overlap is both strength and risk. Strategic investors can accelerate adoption, but commercial relationships may make market demand appear stronger than it would under purely arm’s-length procurement.


Liquidity is uncertain. An eventual IPO must support a valuation far above current levels for venture-style returns, while strategic acquisition at extreme valuations becomes difficult because only a small set of buyers could finance it and antitrust considerations may constrain some obvious acquirers.


Risks to the Industry


Large financings can accelerate competitive innovation, but they can also distort market behavior.


Capital crowding. Well-funded hardware companies can bid aggressively for scarce semiconductor talent and supply capacity, raising costs for smaller entrants.


Supply concentration. More accelerator designs still depend on a small number of foundries, advanced packaging providers and memory suppliers.


Architecture fragmentation. Heterogeneous hardware can improve efficiency but increase software and operational complexity across the ecosystem.


Overcapacity. If inference demand disappoints, capital-intensive accelerator and data-center investments could create stranded or underutilized assets.


Synchronized assumptions. Many current AI infrastructure investments depend on the same premise: rapidly rising inference demand and sustained willingness to pay. Correlated error in that assumption would affect labs, clouds, chipmakers, power developers and infrastructure financiers simultaneously.


Scenario Analysis


Base Case


Etched successfully ramps production, converts a meaningful portion of its current contracts into recognized revenue and demonstrates superior inference economics on selected frontier workloads. It becomes a credible second-source or specialized accelerator supplier for several AI labs, clouds and high-performance enterprises. NVIDIA remains dominant overall, but Etched captures a defensible high-value niche and grows into a major infrastructure company.


Signals supporting this case: several named production customers; independent benchmark validation; repeat orders; evidence of improving gross margins; second-generation silicon delivered on schedule; expansion beyond Jane Street without sacrificing performance.


Upside Case


Inference becomes substantially larger than training in total compute spend, and workloads increasingly reward specialization. Etched’s architecture demonstrates a durable cost and power advantage while its system integration reduces migration friction. Hyperscalers use Etched as a merchant alternative to internal ASIC programs, AI labs adopt the systems at multi-gigawatt scale, and the company becomes an independent platform with economics closer to a leading accelerator vendor than a niche chip supplier.


In this case, a valuation above $100 billion becomes plausible.


Signals supporting this case: multi-gigawatt customer commitments, very strong gross margins, broad model compatibility, major cloud distribution, sustained performance-per-watt advantage over two NVIDIA generations, rapid third-generation product execution.


Downside Case


Etched’s initial systems work but deliver a narrower advantage than expected once real-world utilization, software costs and new NVIDIA platforms are considered. The $1 billion-plus contracts convert slowly, customers retain Etched as experimental capacity rather than core production infrastructure, and hyperscalers prioritize internal silicon. High production spending forces further financing, compressing returns for current investors.


Signals supporting this case: delayed deliveries, limited independent benchmarking, cancellations or contract slippage, continued customer anonymity, heavy pricing discounts, rising inventory, repeated financing before meaningful revenue, slower roadmap execution.


Solten & Co. Thesis


The Etched financing is evidence that the AI accelerator market is moving from a single dominant architecture toward a portfolio of workload-specific compute systems.


The important economic variable is not “Can Etched beat NVIDIA?” in the abstract. It is whether the cost of inference becomes large and repetitive enough that customers are willing to accept hardware and software fragmentation in exchange for materially better tokens per dollar, tokens per watt and latency on specific high-value workloads.


If that threshold has been crossed, Etched does not need to replace NVIDIA. It needs to become economically indispensable for a sufficiently large subset of inference.


The round suggests sophisticated investors believe that subset may be very large.


Counter-Thesis


The strongest counter-thesis is that the market is overestimating the value of specialized silicon while underestimating the value of general-purpose platform integration.


NVIDIA can amortize R&D across a vastly larger installed base, improve hardware every generation, bundle networking and systems, subsidize adoption through financing and maintain developer lock-in through CUDA. Hyperscalers can optimize internally for their own workloads without paying a merchant supplier margin.


Etched therefore occupies a difficult middle position: more specialized and less ecosystem-rich than NVIDIA, but less vertically integrated with end-customer demand than Google or AWS custom silicon.


The company must show that its system-level efficiency advantage is large enough to overcome that structural disadvantage.


Falsification Criteria


The Solten & Co. thesis would weaken materially if several of the following occur:


  • independent production benchmarks show only modest total-cost advantage over NVIDIA or hyperscaler alternatives;
  • customer contracts fail to convert into deployments and recognized revenue;
  • the majority of demand remains concentrated in Jane Street or one or two counterparties;
  • new model architectures materially reduce the efficiency of Etched’s hardware approach;
  • NVIDIA’s next two platform generations close most of the tokens-per-watt or latency gap;
  • Etched requires repeated large financings without corresponding commercial scale;
  • software migration becomes a persistent barrier to production adoption;
  • hyperscalers refuse to adopt merchant specialized inference hardware because internal chips are economically superior.


Key Unknowns


The public investment case remains constrained by missing information. The highest-value unanswered questions are:


  1. What is Etched’s recognized revenue today?
  2. How much of the $1 billion-plus contract value is legally binding and non-cancellable?
  3. What is customer concentration?
  4. What is the expected delivery schedule for those contracts?
  5. What are current and expected gross margins per rack?
  6. What is actual production yield?
  7. What is the all-in system cost per token under realistic production workloads?
  8. How does Etched compare with NVIDIA Blackwell and Vera Rubin under identical model, precision, latency and batch conditions?
  9. What percentage of workloads can run without material software modification?
  10. What foundry, HBM and packaging capacity is contractually secured?
  11. How much additional capital will be required before positive free cash flow?
  12. What are the preference and governance terms in the latest round?
  13. How much ownership did Jane Street obtain?
  14. Which frontier AI companies and cloud providers are under contract?
  15. What proportion of current contracts relate to first-generation versus future-generation systems?


What to Watch Next


The next six to eighteen months should provide far more information than the financing announcement itself.


The critical signals are:


  • additional named customers;
  • independent benchmark publication;
  • production shipment volume;
  • contract conversion to revenue;
  • second and third hardware generation milestones;
  • hyperscaler adoption;
  • broader software ecosystem availability;
  • pricing disclosure or customer total-cost evidence;
  • manufacturing scale and yield;
  • additional fundraising;
  • changes in NVIDIA inference pricing and roadmap;
  • competitive launches from Cerebras, AMD, AWS, Google and other accelerator providers;
  • any evidence that Etched is becoming a standard merchant alternative rather than a specialist system for a narrow set of customers.


Research Exhibits


Exhibit 1 — Etched Valuation Trajectory

The valuation trajectory illustrates how rapidly market expectations have changed. The Series A valuation is intentionally omitted because Etched did not publicly disclose it at the time.


Exhibit 2 — Known Financing Rounds

Public financing records do not fully reconcile to Etched’s stated $1.9 billion total because several rounds were unannounced and historical totals were rounded. The correct approach is to preserve that uncertainty rather than manufacture precision.


Exhibit 3 — What a $21 Billion Entry Valuation Implies

This is an illustrative return-hurdle model, not a valuation forecast. It demonstrates how future dilution raises the exit value required for current investors to achieve venture-style returns.


Sources & Evidence


Primary / company sources


Etched — Frontier Inference Clusters, June 30, 2026

https://www.etched.com/progress/frontier-inference-clusters


Etched — company website and leadership materials

https://www.etched.com/


Etched — $300M financing at $10.3B valuation, July 23, 2026

https://www.globenewswire.com/news-release/2026/07/23/3332366/0/en/Etched-raises-300M-at-a-10-3B-Valuation-to-Scale-Production-of-Frontier-Scale-Inference-Hardware.html


Etched — $700M financing at $21B valuation / first Jane Street delivery, August 18, 2026, company release syndicated by AIwire

https://www.hpcwire.com/aiwire/2026/08/18/etched-raises-700m-at-21b-valuation-and-completes-1st-customer-delivery-to-jane-street/


CoreWeave — Jane Street $6B cloud agreement and $1B equity investment, April 15, 2026

https://www.coreweave.com/news/jane-street-signs-6-billion-ai-cloud-agreement-with-coreweave


NVIDIA — FY2026 annual results

https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Announces-Financial-Results-for-Fourth-Quarter-and-Fiscal-2026/


NVIDIA — FY2026 Form 10-K

https://www.sec.gov/Archives/edgar/data/1045810/000104581026000021/nvda-20260125.htm


Google Cloud — Anthropic expands TPU usage, April 6, 2026

https://www.googlecloudpresscorner.com/2026-04-06-Anthropic-Expands-Use-of-Google-Cloud-and-TPUs


High-quality reporting / research


Reuters — AI chip startup Etched doubles valuation to $21 billion in under a month, August 18, 2026

https://www.reuters.com/technology/ai-chip-startup-etched-valued-21-billion-latest-funding-round-2026-08-18/


Reuters — Etched raises $120 million to develop specialized chip, June 25, 2024

https://www.reuters.com/technology/artificial-intelligence/ai-startup-etched-raises-120-million-develop-specialized-chip-2024-06-25/


Reuters — Jane Street signs $6B AI cloud deal with CoreWeave, April 15, 2026

https://www.reuters.com/legal/transactional/jane-street-signs-6-billion-ai-cloud-deal-with-coreweave-boosts-stake-2026-04-15/


Reuters — Cerebras launches new inference server system, August 19, 2026

https://www.reuters.com/technology/cerebras-launches-new-server-chip-system-designed-speed-ai-chatbots-2026-08-19/


Reuters — Broadcom signs long-term Google custom AI chip agreement, April 6, 2026

https://www.reuters.com/business/broadcom-signs-long-term-deal-develop-googles-custom-ai-chips-2026-04-06/


TechCrunch — Etched Series C at $10.3B valuation, July 23, 2026

https://techcrunch.com/2026/07/23/ai-chip-startup-etched-defies-skeptics-hits-10-3b-valuation-from-big-name-investors/


TechCrunch — Etched Series A / transformer-only strategy, June 25, 2024

https://techcrunch.com/2024/06/25/etched-is-building-an-ai-chip-that-only-runs-transformer-models/


Primary Venture Partners — Etched Series A thesis / company history

https://www.primary.vc/articles/etcheds-series-a-to-revolutionize-ai-hardware


Academic research — The xPU-athalon: Quantifying the Competition of AI Acceleration, 2026

https://arxiv.org/abs/2604.10852


Methodological Note


This report distinguishes disclosed facts, reported terms, estimates and Solten & Co. interpretation.


DISCLOSED FACT — directly supported by a company, regulatory or authoritative primary source.


REPORTED TERM — reported by a credible secondary source but not independently disclosed in full by the relevant company or counterparty.


ESTIMATE — an analytical calculation based on incomplete public data. Assumptions are stated where material.


SOLTEN & CO. INTERPRETATION — our synthesis or inference from the evidence.


The report does not treat contract value as revenue, valuation as enterprise value, or headline round size as sufficient evidence of ownership. Private-company financial statements, cap-table terms, contract schedules and detailed customer economics are not publicly available. Valuation return scenarios are illustrative and do not represent an investment recommendation.


About Solten & Co.


Solten & Co. is an independent research and analysis firm focused on the AI economy, with deeper research emphasis on AI infrastructure, Physical AI, robotics and autonomous systems. We study the technologies, companies, markets, transactions and capital structures shaping the next phase of AI.

NVIDIA Is Becoming the Financing Layer of AI

How equity, guarantees, and Wall Street partnerships are turning compute deployment into a capital-market strategy.

Solten Research Report
August 21, 2026
AI Infrastructure · Capital & Deals

Research Snapshot

Research type: Flagship Research Report

Evidence cut-off: August 21, 2026

Estimated reading time: ~30 minutes

Executive Summary

NVIDIA’s strategic position in artificial intelligence is changing again. The company first became indispensable as the dominant supplier of accelerated computing. It then expanded the competitive boundary through CUDA, networking, systems and full-stack AI infrastructure. In 2026, a third layer has become increasingly visible: NVIDIA is using equity capital, credit support, guarantees and partnerships with global asset managers to help finance the infrastructure that buys and deploys NVIDIA compute.

This is not a side activity. On August 10, NVIDIA announced memoranda of understanding with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to create financing platforms intended to mobilize more than $500 billion of third-party capital for AI infrastructure. NVIDIA described the objective explicitly: turn NVIDIA compute and full-stack AI infrastructure into an investable asset class and create dedicated pools of capital for its ecosystem.

One week later, NVIDIA announced a $1.5 billion investment in SB Energy and credit support for the land, power and shell associated with the initial 4.25 IT-GW at the PORTS-Pike Technology Campus in Ohio. OpenAI has agreed to secure approximately 8 IT-GW at the site. NVIDIA will be the exclusive AI compute infrastructure provider. Four days later, NVIDIA disclosed a minority investment in Cloverleaf Infrastructure, a developer focused on power and sites for data-center projects in the United States.

These transactions extend a pattern already visible in NVIDIA’s relationship with CoreWeave. In January 2026, NVIDIA invested $2 billion in CoreWeave as the companies expanded a relationship designed to support more than 5 GW of AI factories by 2030. NVIDIA’s latest Form 10-Q shows how quickly the financial footprint has grown: non-marketable equity securities increased from $3.24 billion in April 2025 to $42.34 billion in April 2026, while total investment commitments reached $27 billion as of April 26, 2026.

The core Solten & Co. thesis is that NVIDIA is evolving from a semiconductor supplier into a deployment orchestrator. It is not merely selling scarce hardware into demand. It is increasingly helping convert future AI demand into financeable infrastructure projects — and in doing so, it can influence which clouds, data-center developers, energy projects and AI labs reach scale.

That strategy can deepen NVIDIA’s moat. If lenders and infrastructure investors become comfortable underwriting assets around NVIDIA systems, the company gains a financing advantage in addition to a technology advantage. Lower financing friction can accelerate customer buildout, expand the installed base, support CUDA adoption and create additional demand for future NVIDIA generations. The financing mechanism can therefore become self-reinforcing.

But the same mechanism also creates a new risk surface. NVIDIA may increasingly have economic exposure to the success of customers, infrastructure developers and AI demand itself. Guarantees and strategic investments can soften the distinction between independent market demand and supplier-supported demand. If compute remains scarce and utilization stays high, this may look like efficient ecosystem financing. If supply catches up, utilization falls or AI-lab economics disappoint, the residual value of GPU-backed projects and the credibility of compute as collateral could be tested.

The right analytical frame is therefore not simply “circular financing.” That phrase is too broad and often conflates equity investments, customer prepayments, credit guarantees, offtake arrangements and independent third-party debt. The more useful question is: how much of AI infrastructure demand is becoming dependent on balance-sheet intermediation by the companies that benefit from the buildout?

Key Findings

  1. NVIDIA is moving upstream into capital formation. Its August 10 partnerships with six major financial institutions are explicitly designed to create dedicated pools of capital for NVIDIA-based AI infrastructure.
  2. The scale is no longer experimental. The financing platforms target more than $500 billion of third-party capital over time, subject to final agreements.
  3. NVIDIA is also using its own balance sheet. Its April 2026 10-Q reported $42.34 billion of non-marketable equity securities and $27 billion of investment commitments.
  4. Strategic finance is now crossing infrastructure layers. NVIDIA has invested in an AI cloud, a data-center and energy developer, and now a powered-site developer, while also providing credit support for land, power and shell.
  5. The PORTS-Pike structure is especially important. NVIDIA is not simply selling chips into the Ohio campus; it is investing in SB Energy, supporting project credit and securing exclusive NVIDIA compute deployment.
  6. Compute is being marketed as collateral. NVIDIA’s financing thesis depends on the proposition that its systems are transferable, fungible across workloads, supported by a deep offtaker ecosystem and capable of producing long-duration usage-linked revenue.
  7. Financial advantage can reinforce technical advantage. If NVIDIA-based projects obtain cheaper or more abundant capital than alternatives, financing becomes part of platform competition.
  8. The risk migrates from inventory to credit and utilization. A future downturn would test GPU residual values, long-term utilization assumptions, customer credit quality and the willingness of third-party financiers to treat compute as infrastructure.
  9. “Circular financing” is an incomplete diagnosis. The material distinction is whether transactions create artificial demand or simply reduce financing friction around demand that already exists.
  10. The next competitive battlefield may be balance-sheet architecture. NVIDIA’s strategy creates a playbook that Google, Broadcom and others can adapt around their own compute ecosystems.

Table of Contents

  1. What Changed
  2. From Chip Supplier to Deployment Orchestrator
  3. The Balance Sheet Has Become Strategic Infrastructure
  4. The $500 Billion Compute-Financing Experiment
  5. PORTS-Pike: Where the Model Becomes Visible
  6. CoreWeave: The Earlier Prototype
  7. Cloverleaf: Moving Upstream Into Power and Sites
  8. Compute as an Asset Class
  9. The Financing Flywheel
  10. Why This Can Strengthen NVIDIA’s Moat
  11. Where Circularity Is Real — and Where It Is Not
  12. The Credit Question
  13. Implications for AI Clouds and Infrastructure Developers
  14. Implications for Capital Markets
  15. Competitive Responses
  16. Solten & Co. Thesis, Counter-Thesis and Falsification
  17. What to Watch

Sources & Evidence

Methodological Note

About Solten & Co.

Scope & Methodology

This report examines the financial architecture developing around NVIDIA’s AI infrastructure ecosystem. It focuses on strategic equity investments, investment commitments, credit support, guarantees and third-party financing platforms that can affect the rate at which NVIDIA-based infrastructure reaches operation.

Primary evidence includes NVIDIA SEC filings, NVIDIA corporate disclosures, CoreWeave SEC filings and corporate releases, and OpenAI’s PORTS-Pike announcement. Reuters and the Financial Times are used for independently reported context where the underlying contractual details are not fully disclosed publicly.

The analysis distinguishes four categories that should not be collapsed into one number: equity investment, contractual investment commitments, credit support or guarantees, and third-party capital mobilization. These categories create different economic exposures and are not additive.

1. What Changed

In prior AI infrastructure cycles, the main strategic question around NVIDIA financing was whether investments in customers and ecosystem companies were helping stimulate purchases of NVIDIA hardware. By August 2026, that question is too narrow.

The company is now designing capital-market infrastructure. Its August 10 announcement with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR states that the parties intend to establish financing platforms for NVIDIA customers and to mobilize more than $500 billion of third-party capital over time. The company’s language matters: NVIDIA wants compute to be treated as “productive, investable infrastructure.”

This marks a shift from bilateral ecosystem support toward an institutionalized financing channel. The objective is not only to invest alongside customers but to make NVIDIA-based compute legible to credit markets, infrastructure funds and other pools of long-duration capital.

The timing is important. AI infrastructure is simultaneously becoming larger, more power-intensive and more capital-intensive. Individual projects increasingly require tens of billions of dollars across land, power, shell, cooling, networking and compute. Even companies with strong equity valuations do not necessarily want to finance the entire stack with corporate cash. The system therefore needs structures that can separate infrastructure ownership from compute demand and connect AI deployment to outside capital.

2. From Chip Supplier to Deployment Orchestrator

NVIDIA’s original economic model was straightforward: design high-value chips and systems, sell them into a rapidly expanding market, and capture unusually high gross margins through superior performance and ecosystem lock-in.

That model remains intact. NVIDIA reported $81.6 billion of revenue in the first quarter of fiscal 2027, including $75.2 billion from Data Center, with a GAAP gross margin of 74.9%.

But as infrastructure scale increases, the limiting factor is no longer chip demand alone. Customers need land, power, buildings, debt capacity, equity capital and credible long-term offtake. A semiconductor vendor that can reduce those constraints increases the probability that its own systems are deployed.

This creates a logical strategic progression:

  • Own the critical compute platform.
  • Expand into networking, systems and software.
  • Invest in the companies that deploy the platform.
  • Use credit support to improve bankability of infrastructure.
  • Bring institutional capital into the ecosystem.
  • Create a secondary financing market around compute assets.

At the limit, NVIDIA does not need to own the data center or become a bank. It only needs enough influence over capital formation to accelerate compatible infrastructure and preserve NVIDIA as the preferred compute standard.

3. The Balance Sheet Has Become Strategic Infrastructure

NVIDIA’s SEC filings make the shift measurable. Non-marketable equity securities rose from $3.24 billion at April 27, 2025 to $42.34 billion at April 26, 2026. NVIDIA also disclosed $27 billion of investment commitments as of April 26, 2026, subject to contingencies and expected to be made through the remainder of fiscal 2027.

The absolute amounts matter less than the rate of change. NVIDIA has accumulated enough financial capacity that strategic investing can influence ecosystem formation without changing the core economics of the chip business.

At April 26, 2026, NVIDIA also held $13.24 billion of cash and cash equivalents, $37.10 billion of marketable debt securities and $30.24 billion of marketable equity securities. Its first-quarter revenue was $81.6 billion. The company therefore has a balance sheet and cash-generation profile that allows it to support projects at a scale that most suppliers could not contemplate.

This is the strategic asymmetry: NVIDIA can use the profits generated by its dominant position to finance more infrastructure that reinforces that position.

4. The $500 Billion Compute-Financing Experiment

On August 10, NVIDIA announced memoranda of understanding with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR to create independent compute-financing platforms. The stated target is to mobilize more than $500 billion of third-party capital over time.

This should not be interpreted as NVIDIA committing $500 billion. It is a target for capital mobilized through external financing platforms, and final agreements remain to be executed.

The more important feature is institutional design. NVIDIA is attempting to establish a recognizable financing category around compute. Goldman Sachs explicitly referred to creating a market for credit backed by NVIDIA compute. NVIDIA argues that its platform is suited to financing because the assets are broadly adopted, flexible across models and workloads, transferable across customers and operators, and continuously improved through CUDA software.

If financiers accept those premises, AI compute begins to resemble infrastructure equipment that can support debt rather than a rapidly depreciating technology asset that requires mostly equity capital.

That change can materially lower the cost of AI deployment. Infrastructure funds and private credit investors generally demand lower returns than venture equity. Moving part of the capital stack from equity to infrastructure-style credit can expand the number of projects that clear their financing hurdle.

5. PORTS-Pike: Where the Model Becomes Visible

The PORTS-Pike Technology Campus in Pike County, Ohio is the clearest current example of NVIDIA’s expanded role.

OpenAI has agreed to secure approximately 8 IT-GW at the campus. NVIDIA will be the exclusive AI compute infrastructure provider. NVIDIA announced a $1.5 billion investment in SB Energy and said it will provide credit support for land, power and shell associated with the initial 4.25 IT-GW, with an option related to the remaining 3.75 IT-GW.

The structure links four different economic actors:

  • OpenAI provides long-duration compute demand.
  • SB Energy develops the physical campus and associated infrastructure.
  • NVIDIA provides compute and financial support.
  • External lenders and capital markets can finance assets against the combination of demand, project infrastructure and NVIDIA credit support.

This is not traditional semiconductor selling. NVIDIA is helping create the project-finance conditions required for the customer to become large enough to buy future NVIDIA systems at extraordinary scale.

Reuters reported that NVIDIA’s potential guarantees could reach as much as $105 billion over the life of the project and relate to key lease and power obligations. Because the full contracts are not public, that figure should be treated as a reported potential exposure rather than a disclosed current liability.

6. CoreWeave: The Earlier Prototype

CoreWeave provides the most developed case of NVIDIA combining technology, customer economics and strategic capital.

In January 2026, NVIDIA invested $2 billion in CoreWeave common stock. The companies simultaneously announced an expanded relationship intended to accelerate more than 5 GW of AI factories by 2030 and to deploy multiple future NVIDIA platform generations.

The relationship is strategically powerful because CoreWeave converts NVIDIA hardware into rented compute. That broadens NVIDIA’s addressable market beyond customers capable of buying clusters outright. It also creates a specialist cloud that can absorb new GPU generations rapidly and make them available to AI labs and enterprises.

The risk is concentration and interdependence. CoreWeave depends heavily on NVIDIA hardware for competitive differentiation, while NVIDIA benefits when CoreWeave obtains the capital and customers required to keep purchasing new generations. The relationship can be economically rational for both parties without being fully independent.

This is why analysis should focus on the quality of end demand. If CoreWeave utilization and customer contracts are strong enough to support its infrastructure economics, NVIDIA’s capital support is an accelerator. If demand weakens, support can become a mechanism that delays price discovery.

7. Cloverleaf: Moving Upstream Into Power and Sites

On August 21, Reuters reported that NVIDIA made a minority investment in Cloverleaf Infrastructure to develop infrastructure that supports AI data-center projects across the United States.

This extends NVIDIA’s strategy farther upstream. A powered site is not a compute asset, but it is a prerequisite for one. In a market where time-to-power is increasingly scarce, investing in site development gives NVIDIA exposure to the earliest stage of the deployment funnel.

The strategic logic is consistent with PORTS-Pike: reduce the number of infrastructure bottlenecks that sit between theoretical GPU demand and an energized cluster.

This also creates a bridge to Solten & Co.’s broader time-to-power thesis. NVIDIA’s financing strategy and power strategy are converging. The company is not merely ensuring that customers can finance chips; it is increasingly participating in the chain that makes a site financeable, powered and capable of hosting those chips.

Exhibit 3 — NVIDIA Is Moving Upstream Across the AI Infrastructure Capital Stack

8. Compute as an Asset Class

The most consequential claim in NVIDIA’s August 10 announcement is not the $500 billion target. It is the assertion that NVIDIA compute can function as an investable asset class.

That claim requires several conditions:

  1. High utilization. Assets must generate enough usage revenue to service debt.
  2. Transferability. If one customer fails, capacity must be redeployable to another.
  3. Residual value. Older generations must retain enough economic utility to support conservative lending assumptions.
  4. Software durability. CUDA and the surrounding ecosystem must extend useful life beyond the hardware’s initial performance frontier.
  5. Deep offtaker markets. Lenders must believe there will be buyers for compute across AI labs, enterprises, sovereign projects and clouds.
  6. Operational reliability. Facilities must deliver uptime and performance consistent with contracted revenue.

NVIDIA can influence several of these variables directly. CUDA improves fungibility across workloads. DGX Cloud Lepton and cloud partnerships can broaden access to offtakers. Frequent hardware generations can increase demand for new assets, although they also create the depreciation risk that lenders must underwrite.

This tension is central. NVIDIA benefits from rapid product cycles, while credit investors prefer stable residual values. The financing market must reconcile those incentives.

9. The Financing Flywheel

The emerging flywheel can be summarized as follows.

NVIDIA technology generates demand. Equity investments, guarantees, and credit support improve project bankability. Third-party capital finances more infrastructure. More infrastructure deploys more NVIDIA systems. A larger installed base expands the CUDA ecosystem and broadens the set of potential offtakers. That makes future NVIDIA-based projects easier to finance.

The flywheel matters because platform dominance can become embedded in financing standards. Once lenders build underwriting models around NVIDIA systems, project templates, resale assumptions, and utilization data can create institutional familiarity. Familiarity lowers transaction costs. Lower transaction costs can reinforce standardization.

This is analogous to other infrastructure markets where financing ecosystems accumulate around dominant equipment, operating models or contractual standards.

10. Why This Can Strengthen NVIDIA’s Moat

NVIDIA’s moat is usually described in technical terms: accelerator performance, CUDA, networking, system design and developer ecosystem. Financing adds another layer.

First, it can expand the customer base. Customers that cannot self-finance large clusters can access third-party capital.

Second, it can accelerate deployment. Credit support can move projects forward before customers accumulate enough cash or equity capital.

Third, it can increase switching costs. Financing documents, residual-value assumptions and infrastructure design may be built around NVIDIA architectures.

Fourth, it can defend against alternative accelerators. A technically credible competing chip may still face a financing disadvantage if lenders, developers and operators are more comfortable with NVIDIA-backed systems.

Fifth, it can make NVIDIA a gatekeeper in ecosystem formation. Strategic investment can influence which clouds, infrastructure developers and adjacent suppliers reach scale.

This is why the financing layer should be analyzed as part of competition, not merely corporate treasury activity.

11. Where Circularity Is Real — and Where It Is Not

The term “circular financing” has become shorthand for transactions in which an AI supplier finances a customer that then uses the proceeds to buy the supplier’s product. But the label can obscure important differences.

A direct equity investment in a customer can be circular in economic effect if the investment is required for the customer to purchase the investor’s product. A guarantee can create similar exposure if it is necessary for lenders to finance an otherwise uneconomic project.

But third-party financing is not automatically artificial demand. If an AI lab has a credible long-term contract for compute and infrastructure investors independently underwrite the project, supplier participation can simply reduce information and execution friction.

The key tests are therefore:

  • Would the end customer demand exist without supplier financing?
  • Is the project economically viable at market financing terms?
  • Are lenders taking genuine independent risk?
  • Does the supplier retain material downside through guarantees or residual-value support?
  • Are utilization and contract assumptions externally verifiable?
  • Does the transaction shift risk or merely hide it?

This framework is more useful than treating every ecosystem investment as evidence of a bubble.

12. The Credit Question

Equity investors can tolerate volatility and long periods before profitability. Credit investors require a different kind of evidence: contracted cash flow, asset recovery value, predictable utilization and enforceable security.

That means the next stage of AI infrastructure will generate new datasets. Lenders will need to understand GPU useful life, resale markets, utilization curves, power-price exposure, customer concentration, software obsolescence and the cost of moving hardware between operators.

In conventional digital infrastructure, lenders can underwrite fiber routes, towers and data-center leases using long operating histories. GPU clusters do not yet have that history at current scale.

That is the hidden importance of NVIDIA’s Wall Street partnerships. The company is not merely seeking more capital. It is helping create the underwriting methodology for a new category of credit.

13. Implications for AI Clouds and Infrastructure Developers

For AI clouds, NVIDIA-backed financing can lower the cost of growth. But it can also increase strategic dependence on one platform and encourage faster expansion than internally generated cash flow would support.

For data-center developers, access to NVIDIA-aligned demand and credit support can improve project financeability. The more valuable the NVIDIA ecosystem becomes to lenders, the more attractive it may be to design facilities around NVIDIA deployment standards.

For power developers, the relationship is moving even earlier in the lifecycle. PORTS-Pike and Cloverleaf show that NVIDIA has an incentive to secure land and power before a cluster exists.

The infrastructure stack is therefore becoming vertically coordinated without necessarily becoming vertically owned.

14. Implications for Capital Markets

If compute-backed credit becomes institutionalized, it can create a large new market spanning private credit, infrastructure debt, securitization, equipment finance and project finance.

The attraction is obvious. AI infrastructure can generate high contracted revenue, and hyperscalers or frontier labs can function as powerful offtakers. The risk is that multiple layers of the capital stack ultimately depend on the same underlying assumption: continued rapid growth in AI demand.

That creates correlation. Equity investors may believe they are financing a cloud company, credit investors a data center, infrastructure investors a power project and NVIDIA shareholders a semiconductor business — while all four returns may depend on the same end customer continuing to buy AI compute.

The financial system can therefore diversify legal entities without fully diversifying economic exposure.

15. Competitive Responses

NVIDIA’s strategy is unlikely to remain unique.

Google has incentives to use its balance sheet and cloud ecosystem to finance TPU deployments. Broadcom’s custom accelerator ecosystem can be paired with structured finance around hyperscaler or AI-lab capacity. Large cloud providers can support partners through leases, guarantees and offtake commitments.

Once financing becomes a competitive tool, accelerator competition can expand from performance-per-dollar into capital-per-deployed-compute: which platform can mobilize the cheapest, fastest and most scalable financing around its ecosystem.

This may favor companies with investment-grade balance sheets, large cash flows and established relationships with global capital providers.

16. Solten & Co. Thesis, Counter-Thesis and Falsification

Solten & Co. Thesis

NVIDIA is becoming the financing layer of the AI infrastructure ecosystem. Its strategic advantage increasingly combines technology, software, installed base, balance-sheet capacity and the ability to mobilize third-party capital. If compute develops into an accepted infrastructure asset class, NVIDIA can reinforce its platform moat by lowering the financing friction of NVIDIA-based deployment.

Counter-Thesis

The financing strategy may be a temporary response to an unusually tight market rather than a durable moat. GPU supply could normalize, customers could diversify toward custom accelerators, and rapid hardware generations could make residual-value underwriting difficult. If AI infrastructure returns compress, lenders may discover that “compute as an asset class” behaves more like cyclical technology equipment than long-duration infrastructure. NVIDIA could then be left with investment losses, guarantee exposure and customers that expanded too aggressively.

Falsification Criteria

  • The announced $500 billion financing platforms fail to reach final agreements or mobilize material third-party capital.
  • NVIDIA-backed projects require progressively larger guarantees to clear financing markets.
  • Secondary-market values for older NVIDIA systems fall too quickly to support meaningful secured lending.
  • Utilization or pricing for AI compute declines enough to make debt service materially less robust.
  • Alternative accelerator ecosystems obtain comparable financing terms without NVIDIA’s installed-base advantage.
  • Strategic investments generate repeated impairments or fail to translate into durable NVIDIA platform demand.
  • Credit investors materially increase spreads or reduce advance rates on GPU-backed infrastructure.

17. What to Watch

Final terms of the $500 billion financing platforms. The memoranda of understanding are not yet final agreements. Watch how much direct risk NVIDIA retains.

NVIDIA’s August 26 earnings and filings. Additional disclosure on investment commitments, guarantees and strategic investments could clarify the scale of balance-sheet exposure.

PORTS-Pike financing. The eventual debt structure, guarantee mechanics and lender base will provide a benchmark for large AI project finance.

GPU-backed lending terms. Advance rates, depreciation assumptions, covenants and collateral substitution rules will reveal how credit markets value compute.

CoreWeave utilization and leverage. It remains one of the most important real-world tests of whether specialist AI-cloud economics can support large infrastructure commitments.

Cloverleaf project conversion. Watch whether powered-site origination translates into NVIDIA-exclusive or NVIDIA-preferred deployments.

Competitor financing structures. Google, Broadcom and hyperscalers are the most important reference points.

Residual values. The resale and redeployment economics of Hopper, Blackwell, Rubin and subsequent generations will determine whether compute behaves like durable collateral.

Sources & Evidence

Primary sources

NVIDIA — AI Compute Infrastructure Financing Platforms, August 10, 2026

https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Partners-With-Apollo-BlackRock-Blackstone-Brookfield-Goldman-Sachs-and-KKR-to-Establish-AI-Compute-Infrastructure-Financing-Platforms-to-Mobilize-Over-500-Billion-of-Third-Party-Capital/default.aspx

NVIDIA — PORTS-Pike Technology Campus Credit Support, August 17, 2026

https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Guarantees-SB-Energys-PORTS-Pike-Technology-Campus-in-Ohio-to-Exclusively-Host-NVIDIA-AI-Compute/default.aspx

OpenAI — OpenAI joins PORTS-Pike project, August 17, 2026

https://openai.com/index/openai-joins-ports-pike-project/

NVIDIA — Form 10-Q for quarter ended April 26, 2026

https://www.sec.gov/Archives/edgar/data/1045810/000104581026000052/nvda-20260426.htm

NVIDIA — Fiscal 2027 First Quarter Results, May 20, 2026

https://investor.nvidia.com/news/press-release-details/2026/NVIDIA-Announces-Financial-Results-for-First-Quarter-Fiscal-2027/default.aspx

CoreWeave — Form 8-K / NVIDIA $2 billion investment, January 2026

https://www.sec.gov/Archives/edgar/data/1769628/000176962826000044/crwv-20260123.htm

CoreWeave / NVIDIA — Expanded AI Factory Collaboration, January 26, 2026

https://www.sec.gov/Archives/edgar/data/1769628/000176962826000044/ex991pressrelease_final.htm

High-quality reporting

Reuters — NVIDIA invests in Cloverleaf Infrastructure, August 21, 2026

https://www.reuters.com/technology/nvidia-invests-data-center-developer-cloverleaf-infrastructure-2026-08-21/

Reuters — NVIDIA to provide up to $105 billion guarantee for OpenAI Ohio data center, August 17, 2026

https://www.reuters.com/business/media-telecom/nvidia-invest-15-billion-sb-energy-under-openai-data-center-deal-2026-08-17/

Financial Times — NVIDIA looks well placed to benefit from the next stage of the AI boom, August 20, 2026

https://www.ft.com/content/b388be2e-67bd-4056-abd2-234e17819a98

Methodological Note

This report does not aggregate NVIDIA equity investments, investment commitments, potential guarantees and third-party capital targets into a single exposure number because they represent different economic obligations.

The $500 billion figure is a target for third-party capital to be mobilized by financing platforms and is subject to final agreements. The reported potential $105 billion PORTS-Pike guarantee is based on Reuters reporting and is not treated as an existing funded liability. NVIDIA’s disclosed $1.5 billion SB Energy investment and credit support for initial land, power and shell capacity are treated separately.

The term financing layer is a Solten & Co. analytical concept. It describes NVIDIA’s emerging role in reducing capital-formation friction around AI infrastructure; it does not imply that NVIDIA is a regulated bank or that all NVIDIA ecosystem financing is controlled by NVIDIA.

The Return of Marginal Cost

How to underwrite AI-native software when usage, quality and economics move
together.

KEY THESIS  The correct unit of analysis is the accepted workflow—not the seat, token or API call. Falling model prices help, but durable economics appear only when value captured per accepted workflow improves faster than total workflow intensity, rework and non-model variable costs.

Research snapshot

Field Detail
Research question How should investors underwrite AI-native application software when marginal cost, output quality and customer value all vary with usage?
Evidence cut-off 25 August 2026
Audience Family offices, venture/growth investors, lean investment teams and strategy leaders
Reading time 12–15 minutes
Scope Application-layer economics; not a company rating, financing analysis or valuation opinion

Executive summary

Software investors learned to value businesses whose cost of serving an additional user approached zero. AI reintroduces a meaningful variable-cost stack: model inference, tool calls, retrieval, orchestration, evaluation, human review and support. The familiar SaaS shorthand—annual recurring revenue, seats and gross margin—still matters, but it can hide whether greater adoption makes the product economically stronger or merely more expensive to operate.

The market’s first instinct has been to treat inference prices as the answer. That is too simple. Stanford’s AI Index found that the cost of querying a model with GPT-3.5-level benchmark performance fell from about $20 per million tokens in November 2022 to $0.07 by October 2024, a decline of more than 280 times.[1] Yet an agent that makes five times as many model calls, uses longer contexts or triggers more tools can consume the entire saving. An 80% decline in unit price combined with a fivefold increase in workload leaves total model cost unchanged.

Quality makes the equation harder. In a field study of 5,179 customer-support agents, generative AI raised issues resolved per hour by 14% on average and by 34% for novice and lower-skilled workers.[5] In a separate experiment involving 758 consultants, people working inside the technology’s capability frontier completed more tasks, worked faster and produced higher-quality output; on a task outside that frontier, AI users were 19 percentage points less likely to reach the correct answer.[6] The economic value of AI therefore depends on the workflow, the user and the cost of detecting failure—not merely on access to a capable model.

Our conclusion is that investors need a new primary unit: contribution margin per accepted workflow. “Accepted” means the customer or a defined control process accepts the output without material rework, reversal or undisclosed human completion. Revenue should be measured against every variable cost required to produce that accepted result, including failed attempts and escalations. This approach makes unlike pricing models comparable and exposes companies whose apparent automation is funded by invisible labour or unchecked risk.

What changed

  • Intelligence became a metered input. API calls, context length, output length, tools and agent loops can all scale with use.[8], [13], [14]
  • Quality became part of unit economics. Evaluation, monitoring and human review are operating costs, especially where errors are consequential.[7], [20], [21]
  • Pricing moved beyond seats. Vendors now combine subscriptions, credits, usage and outcomes, shifting cost and quality risk between buyer and seller.[9], [10], [12], [23]
  • Model choice became an optimisation layer. Routing, caching and asynchronous processing can reduce cost, but add engineering and governance complexity.[15]–[18], [24], [25]
  • Gross-margin dispersion widened. Selected high-growth private AI companies report economics far below mature public SaaS benchmarks.[2]–[4]

Exhibit 1. Benchmark orientation: the margin gap is real, but the samples are not comparable

Sources: Salesforce FY2025 Form 10-K; ServiceNow FY2025 Form 10-K; Bessemer State of AI 2025. Salesforce figure calculated as 1 − $6.198bn / $35.679bn. Bessemer figures are selected private-company averages, not audited market benchmarks.[2]–[4]

The first mistake: treating token deflation as margin expansion

Model prices have fallen quickly, and providers offer cheaper cached input, asynchronous batches and smaller models.[13]–[15], [24], [25] Those mechanisms can improve cost. They do not determine total workflow economics. A workflow may become more ambitious as models improve: longer contexts, more retrieval, parallel agents, repeated reasoning, tool calls and verification. In agentic systems, model calls can branch or loop. Both Anthropic and the major cloud platforms advise using the simplest architecture that meets the task because added autonomy trades cost and latency for performance.[16]–[18], [26], [27]

Exhibit 2. Unit-cost deflation versus workload expansion

Source: Solten & Co. illustrative model. Each cell is (1 − unit-price decline) × workload multiplier. It excludes non-model costs and is not a forecast.

The implication is practical. Management should report both the price paid per unit of compute and the number of units required per accepted result. If model cost per token falls 50% while tokens per accepted workflow triple, model cost per accepted workflow rises 50%. A company that highlights the first number and omits the second is not showing its economics.

The second mistake: measuring automation without acceptance

An automation rate can overstate value if it counts attempts rather than accepted results. A workflow may appear automated while customers reopen cases, employees rewrite the output or a hidden operations team completes exceptions. NIST treats confabulation and downstream reliance as material risks; Google’s deployment guidance describes evaluation as a core operating process and notes that manual evaluation can become a bottleneck.[7], [20]

The quality-adjusted automation rate should therefore be calculated as accepted outcomes divided by attempted workflows. The definition of acceptance must be tied to the customer’s job: a support resolution that is not reopened, code that passes tests and is merged, a claim that survives audit, or a document approved without material rewrite. Intercom’s published approach separates AI involvement from resolution and charges for defined outcomes rather than unsuccessful attempts, illustrating the direction of travel even though the exact commercial definition remains vendor-specific.[10], [11]

Exhibit 3. A four-layer underwriting hierarchy

Source: Solten & Co. framework.

The six metrics that matter

Metric Definition Why investors need it
Contribution margin / accepted workflow Revenue less all variable model, tool, infrastructure, review, support and risk costs, divided by accepted workflows Reveals whether usage creates economic value
Quality-adjusted automation Accepted outcomes ÷ attempted workflows Prevents failed attempts and hidden labour from appearing automated
Workload elasticity Change in model calls, tokens and tools per workflow relative to unit-price change Tests whether cost deflation survives product ambition
Cost-to-serve distribution P50, P90 and P99 variable cost by customer/cohort/workflow Exposes heavy users and tail-risk contracts
Retention after novelty Cohort retention and expansion after initial experimentation Separates durable workflow ownership from curiosity
Provider dependency Share of cost and quality tied to one model/provider; time and quality loss to switch Measures bargaining power and resilience

Pricing is a risk-allocation decision

Seat pricing gives customers budget certainty but leaves the vendor exposed when usage varies widely. Pure usage pricing transfers much of that risk to the buyer, though it can weaken adoption. Outcome pricing aligns with value only where the result is observable and reversals are measurable. Hybrid pricing—base subscription plus included credits or usage—often provides the best bridge because it combines predictability with a limit on unbounded cost. GitHub Copilot’s plans, for example, combine subscription tiers with included AI credits; Stripe documents subscription, usage, outcome and hybrid patterns for AI companies.[8], [9], [12], [23]

What investors should ask

  • What exactly is an accepted outcome, and how often is it reversed, reopened or materially edited?
  • Show revenue, model cost, tool cost, human review and support per accepted workflow—monthly and by cohort.
  • How do P90 and P99 customers compare with the median? Which contracts are contribution-negative?
  • If model prices fall 80%, how much more inference does the product consume? If prices rise or discounts disappear, what reprices?
  • How much labour sits outside cost of revenue? What happens to gross margin if evaluation and review are classified consistently?
  • Does retention persist after experimentation? Is expansion caused by greater customer value or merely by more metered usage?
  • Can the company route across models without losing quality? What proprietary context, distribution or integration survives model commoditisation?

Counter-thesis

The strongest counterargument is that this framework may overstate the break from SaaS. Inference prices could fall faster than workloads expand; products could standardise; customers could continue to prefer simple subscriptions; and many AI features may become low-cost functionality inside conventional software. If those conditions hold, mature AI applications could converge toward classic software margins. The framework would then remain useful mainly during the transition.

That counter-thesis is falsifiable. We would reduce the weight placed on accepted-workflow economics if several conditions persist across cohorts: model and tool cost per workflow falls faster than usage expands; human escalation approaches zero without worsening outcomes; P90 cost-to-serve converges toward the median; retention remains strong after novelty; and vendors achieve public-software gross margins without restricting useful consumption. Until then, the burden of proof should remain on the unit economics.

What to watch

  • Contribution margin per accepted workflow, especially for mature cohorts.
  • Tokens, model calls and paid tool calls per workflow as capability expands.
  • Reopen, reversal, escalation and material-edit rates—not only vendor-reported automation.
  • P90/P99 cost-to-serve and the share of negative-contribution customers.
  • Pricing migration: unlimited seats toward credits, usage caps, outcomes or hybrids.
  • Multi-model routing, caching and batch adoption, with quality held constant.
  • Retention and expansion after pilots convert into production workflows.
  • Gross-margin reconciliation: whether human operations, evaluation and support sit in cost of revenue.

Conclusion

AI-native software can become an exceptional business. It can also look like software while carrying the economics of a service, an infrastructure layer or an insurance contract. The distinction is not visible in ARR alone. It appears at the level of the accepted workflow: what the customer values, what it costs to deliver reliably, how often automation truly succeeds and who bears the tail risk. The companies that learn to improve that equation—through product design, routing, proprietary context, distribution and disciplined pricing—will turn cheaper intelligence into durable margin. The rest may discover that marginal cost did not disappear. It merely moved.

Sources and evidence

Evidence cut-off: 25 August 2026. Vendor pricing and implementation pages are used to document commercial structures and technical mechanisms, not to validate vendor performance. Private-company benchmarks are attributed and treated as directional. Adjacent citations are separated for legibility.

  1. Stanford HAI, AI Index 2025: inference cost decline for GPT-3.5-level performance. Source
  2. Bessemer Venture Partners, The State of AI 2025: private-company growth and gross-margin archetypes. Source
  3. Salesforce FY2025 Form 10-K: subscription and support revenue and cost. Source
  4. ServiceNow FY2025 Form 10-K: subscription gross-profit percentage. Source
  5. NBER, Generative AI at Work: field study of 5,179 customer-support agents. Source
  6. Dell’Acqua et al., Organization Science, Navigating the Jagged Technological Frontier. Source
  7. NIST AI 600-1, Artificial Intelligence Risk Management Framework: Generative AI Profile. Source
  8. Stripe, AI companies and usage-based billing. Source
  9. Stripe, AI pricing models. Source
  10. Intercom, Fin AI Agent outcomes and outcome pricing. Source
  11. Intercom, Fin AI Agent automation rate. Source
  12. GitHub, Copilot plans and included AI credits. Source
  13. OpenAI API pricing. Source
  14. Anthropic API pricing and prompt-caching structure. Source
  15. Google Gemini API, context caching. Source
  16. Anthropic, Building effective agents. Source
  17. AWS Bedrock, Intelligent Prompt Routing. Source
  18. AWS, Generative AI Lens — Well-Architected Framework. Source
  19. Google Cloud Architecture Framework, AI and ML cost optimisation. Source
  20. Google Cloud, deploy and operate generative AI applications. Source
  21. OpenAI API reference, Evals. Source
  22. AWS Bedrock, cost allocation by request. Source
  23. Stripe, token-based billing implementation patterns. Source
  24. OpenAI, Prompt Caching. Source
  25. OpenAI API reference, Batch API. Source
  26. Google Cloud, choosing a design pattern for an agentic AI system. Source
  27. AWS Prescriptive Guidance, cost optimisation for agentic AI. Source

Research disclosure

This report is independent research for informational purposes. It is not investment, legal, tax or accounting advice and does not recommend a security or transaction. The analysis relies on public information available by the evidence cut-off. Illustrative scenarios are analytical tools, not forecasts. Private-company operating data are incomplete; readers should obtain company-level cohort, billing, inference and support records before making an investment decision.

Clarity Before Growth

Over the past month, I found myself thinking less about growth and more about what actually drives it. That may seem counterintuitive given the environment we operate in, but most business discussions eventually return to growth — revenue, customers, market share, and headcount. Growth has become the default measure of progress, to the point where we rarely ask whether the underlying business is actually becoming better as it scales. We assume growth and strength move together. Increasingly, I suspect they do not.

Part of that realization came from conversations with founders and operators over the past weeks. The details varied, but the pattern felt consistent. The challenge was rarely effort, intelligence, or opportunity. The challenge was visibility. People were working hard. Teams were growing. Initiatives were moving. Yet there was often surprising uncertainty around a simple question: what is actually driving performance inside the business?

The longer I work with companies, the more convinced I am that visibility deteriorates faster than most leaders realize. This is one of the strange side effects of success. As organizations grow, they accumulate customers, employees, systems, processes, reports, dashboards, and layers of management. Each addition is intended to improve control and understanding. Yet most leaders describe the opposite. They have more information than ever and less confidence in their ability to understand what is actually happening.

This has changed how I think about complexity. I used to view it as a natural consequence of scale. Large organizations are inherently more complicated than small ones. That is obvious. What seems less obvious now is how much complexity organizations create voluntarily. Very little of it arrives through a single decision. Instead, it accumulates gradually through hundreds of small accommodations that appear entirely reasonable at the time.

A process breaks, so a workaround is introduced. Reporting becomes inconsistent, so another review layer is added. Communication becomes difficult, so another meeting appears on the calendar. A system no longer reflects operational reality, so a spreadsheet bridges the gap. None of these looks particularly dangerous in isolation. Most are practical responses to immediate problems. Yet over time, they form a parallel operating system that nobody intentionally designed.

The same dynamic exists outside organizations as well. Individuals accumulate unnecessary layers just as companies do.

This month, I spent considerable time simplifying my own professional architecture. On the surface, these decisions appeared administrative — consolidating platforms, retiring projects, removing overlapping brands, and reducing the number of places where content lives. Yet the more I worked through them, the more they felt connected to the same pattern I see inside companies.

We often assume progress comes from adding something new. A new initiative. A new product. A new channel. Sometimes it does. More often than we admit, progress comes from removing unnecessary layers that have quietly accumulated over time.

There is a tendency in business to celebrate expansion while overlooking concentration. Growth feels productive because it is visible. Simplification often feels passive because the results are less immediate. Yet some of the strongest businesses I have encountered share a common characteristic: they are remarkably disciplined about protecting clarity. They understand that every new layer carries a cost. Every new initiative creates additional complexity. Every new system introduces another coordination point. Scale may be inevitable. Unnecessary complexity usually is not.

This idea has influenced how I think about business performance itself. I find myself less interested in growth as an isolated outcome and more interested in the relationship between growth and structural integrity. Is the organization becoming easier to operate as it scales, or more dependent on a handful of individuals? Are decisions becoming clearer, or more obscured? Is visibility improving, or deteriorating? Is complexity creating leverage, or merely multiplying itself?

These questions rarely appear in quarterly reports. Yet they often determine what happens next.

Perhaps this is why so many businesses appear healthy right before significant problems emerge. Leadership watches the visible indicators because those are easy to measure. Revenue is growing. Demand is strong. The company is hiring. Customers continue arriving. Meanwhile, the less visible aspects—structural clarity, operational integrity, signal-to-noise ratio, decision quality—receive less attention because they are harder to quantify. The organization continues moving forward. Leadership gradually loses the ability to distinguish between growth and strength.

Growth is an outcome. Strength is a capability. One can create the appearance of success for a surprisingly long time without the other. The organizations I admire most are not simply growing. They are becoming more resilient, more understandable, and more capable as they grow. They are improving the quality of the system itself rather than relying on momentum to carry them forward.

In a business environment that constantly rewards expansion, I found myself increasingly drawn to the opposite question: what would happen if we spent more time protecting clarity than pursuing complexity?

I suspect many organizations would become significantly stronger than they realize.

How Momentum Changes Decision Quality

Momentum is one of the most celebrated forces in business. Investors look for it, leadership teams pursue it, employees feel energized by it, and customers respond to it. When a company is growing quickly, winning new customers, attracting attention, and hitting milestones, momentum creates a sense that the organization is moving in the right direction. The problem is that momentum changes how decisions are made.

Most leaders understand the risks of stagnation. Far fewer recognize the risks that emerge when things appear to be working. Some of the most expensive mistakes in business occur during periods of strong momentum rather than periods of obvious difficulty. When companies struggle, assumptions are questioned naturally. Leadership becomes cautious. Performance is scrutinized. Decisions receive greater examination because the cost of being wrong feels immediate.

Momentum often creates the opposite environment. As positive signals accumulate, leadership becomes increasingly confident that the existing direction is correct. Recent success is beginning to influence how future decisions are evaluated. Ideas that support the current narrative receive less resistance. Information that contradicts the narrative receives less attention. The organization gradually shifts from asking whether it is right to assuming it is right. This transition rarely happens deliberately. No executive team gathers in a conference room and decides to become less objective. The process is far more subtle. Success changes incentives, expectations, and how people interpret information.

When momentum is strong, questioning assumptions can begin to feel disruptive. Teams become reluctant to slow progress. Managers avoid raising concerns that might be perceived as obstacles. Employees become increasingly focused on execution and less focused on validation. Over time, the organization develops a preference for confirmation over investigation.

The challenge is that momentum itself provides very little information about the quality of the underlying decisions. A business may be experiencing momentum because its strategy is working exceptionally well. It may also be experiencing momentum because favorable market conditions are temporarily masking structural weaknesses. From inside the organization, those two situations can feel remarkably similar. This is one reason growth can become dangerous. Growth creates resources, opportunities, and confidence, but it also creates distance between leadership and reality. As organizations become larger, information travels through more layers. Operational complexity increases. Visibility decreases. Decisions become increasingly influenced by summaries, dashboards, and interpretations rather than direct observation.

Under those conditions, momentum can become self-reinforcing. Strong performance encourages additional investment. Additional investment increases expectations. Higher expectations make questioning assumptions more difficult. The organization becomes increasingly committed to the existing narrative because so much has already been built around it. The larger the commitment becomes, the more psychologically expensive re-examination becomes.

This dynamic appears repeatedly across industries. Companies expand into new markets because existing growth creates confidence. Businesses hire aggressively because recent success suggests future success is inevitable. Investors increase funding because momentum appears to validate the underlying thesis. Leadership teams approve increasingly ambitious initiatives because previous decisions seem to have worked. Sometimes those decisions are correct. Sometimes, momentum delays the discovery that they are not.

The most disciplined organizations understand that momentum should not replace validation. In fact, they often become more skeptical as momentum increases rather than less. They recognize that periods of success can distort judgment just as easily as periods of failure. Strong leadership teams intentionally create mechanisms that challenge assumptions even when results look positive. They continue examining customer behavior, operational performance, economic fundamentals, and execution quality. They resist the temptation to assume that recent outcomes automatically justify future decisions.

This requires a degree of intellectual discipline that becomes increasingly rare as momentum accelerates. The pressure to keep moving is powerful. Slowing down to investigate can feel unnecessary. Yet the cost of ignoring weak signals often grows alongside the momentum itself. By the time contradictions become visible, the organization may have already committed significant capital, hired additional teams, expanded operational complexity, or made strategic decisions that are difficult to reverse.

The irony is that momentum is not inherently dangerous. Most organizations would gladly choose momentum over stagnation. The danger emerges when momentum begins influencing judgment. Success becomes problematic only when it reduces curiosity. Growth becomes risky only when it replaces scrutiny.

The strongest businesses do not assume momentum proves they are right. They treat momentum as a condition to be understood rather than evidence that understanding is no longer necessary. That distinction appears small on the surface, but in practice, it often determines whether momentum becomes a durable advantage or the beginning of a much larger problem.

The evidence gap is a company-building problem.

In 100% of the startup packages we reviewed, the same four questions remained unresolved.

Could commercial traction be traced to account-level records?

What was the company’s current financial position, burn, and runway?

What would the proposed financing mean for ownership and control?

Which product or technical claims had been validated with primary evidence?

This is an internal screening observation, not a market-wide benchmark. It does not tell us whether the companies were strong or weak investments. It tells us that the submitted materials could not answer questions that matter before capital is committed.

The more interesting issue is what this inability may reveal about the company itself.

Investors ask for customer schedules, financial statements, cap tables, and validation records because they need to understand an opportunity. But those records also help founders decide whom to serve, what to build, how to price, where to spend, and which risks deserve attention.

A company that cannot produce this evidence may have a fundraising problem. It may also have a management problem that began long before the financing process.

Commercial evidence shapes the company
“Customers” can mean paying accounts, pilots, design partners, trial users, signed contracts, verbal commitments, or logos that have not been active for months.

When those categories are blended together, the company loses more than credibility with investors. It loses the ability to see its own commercial reality.

An account-level customer record should establish who the legal customer is, what they purchased, when the relationship began, what was contracted, invoiced, and collected, which product features they use, and whether they renewed or left.

That record changes the questions management can answer.

Which customer segment reaches value fastest? Which accounts require heavy implementation work? Which product behavior predicts renewal? Is expansion coming from a repeatable motion or from exceptional founder involvement? Are reported results representative, or are they concentrated in one unusually successful deployment?

Without this information, a company may continue building for the customer described in its pitch rather than the customer demonstrated by its operating history.

That distinction shapes the future product. Reliable customer evidence can show which features belong in the core workflow, which should remain services, and which roadmap ideas have no commercial reason to exist. It can reveal that the apparent ideal customer is difficult to acquire, expensive to support, or unwilling to renew.

The same evidence that supports a traction claim can therefore force a better product decision.

Financial clarity changes how capital is used
A financing round is often presented through a target amount and several broad spending categories: product, hiring, sales, expansion, or infrastructure.

Those categories say little about whether the amount is sufficient or what the capital is expected to accomplish.

Current cash, monthly burn, liabilities, gross margin, contribution margin, hiring dates, and a monthly forecast turn a fundraising target into an operating plan. They show when the company may run out of money, which assumptions drive that date, and whether the proposed round reaches a milestone that changes the next financing conversation.

This matters well beyond runway.

A company may report growing revenue while losing money on its most active customers. Usage can increase faster than gross profit. A low acquisition cost can hide poor retention, refunds, implementation work, or support expense. An attractive annualized revenue figure can be built on a temporary month, prepaid contracts, or a customer mix that will not repeat.

None of these possibilities proves that the business is unsound. They show why revenue alone is insufficient for managing it.

Financial discipline helps management distinguish growth that compounds from growth that consumes cash. It informs pricing, contract structure, hiring pace, product limits, vendor negotiations, and the timing of expansion. It also makes tradeoffs visible earlier, while the company still has room to change course.

Capital does not correct unclear economics. It often allows them to continue for longer.

Ownership records shape future choices
Cap tables and financing documents are sometimes treated as legal housekeeping to be cleaned up when an investor asks.

In practice, ownership affects who is motivated, who can make decisions, how much dilution the next round may create, and whether future investors will accept the structure they inherit.

A current and pro forma cap table should include founder ownership, vesting, the option pool, prior equity, SAFEs, notes, warrants, side rights, and the effect of the proposed financing. When these items are incomplete or scattered across documents, management may not understand the economic consequences of the round it is raising.

That uncertainty can shape hiring and retention. It can complicate governance. It can make a seemingly acceptable financing expensive under a future conversion scenario. It may also expose disagreement between the company’s operating plan and the incentives of the people expected to execute it.

The financing instrument matters for the same reason. Capital arrives with terms, rights, expectations, and future consequences. Understanding those consequences is part of designing the company, not merely documenting the transaction.

Validation determines what the product becomes
Product claims often sound precise: faster processing, lower cost, improved conversion, greater accuracy, higher recovery, or better customer outcomes.

A percentage without its baseline, denominator, period, cohort, source system, and method of calculation remains difficult to interpret. The same applies to technical claims that lack a test configuration, acceptance criteria, failure record, or independent review.

For investors, missing validation creates uncertainty. For product teams, it creates the risk of learning the wrong lesson.

If a result cannot be reproduced, management cannot know what caused it. The product may receive credit for an effect produced by manual work, customer selection, implementation effort, or an unusual operating environment. A successful pilot may lead to a broad roadmap before the team has established which part of the solution created value.

Validation imposes useful discipline. It requires the company to separate what is live from what is in pilot, beta, or development. It forces a definition of success before the result is known. It records failures and limitations instead of allowing them to disappear into the next version of the story.

That process helps the company decide what to improve, what to stop building, and what deserves further investment.

Fundraising readiness should begin as operating discipline
The usual response to investor questions is to build a data room.

That is useful, but timing matters. If the records are assembled only when a financing process begins, the company receives their management value too late. Months of product, hiring, and spending decisions may already have been made without them.

A better approach is to maintain a compact evidence system as part of normal operations:

A dated customer master that separates prospects, pilots, paid accounts, inactive customers, and renewals.
A monthly financial pack connecting revenue, cash, burn, margin, liabilities, and forecast.
A product evidence register linking material claims to definitions, tests, results, limitations, and source records.
A controlled ownership and financing record showing current securities and the effects of proposed transactions.

These records do not need to become an administrative burden. Their purpose is to keep the company’s decisions connected to what is actually happening.

They will not guarantee that a startup raises capital. They will not make a weak product strong or remove the uncertainty inherent in an early-stage company. They can, however, make problems visible sooner and help management respond while options still exist.

That has a direct relationship to financial success. Better customer evidence can improve product focus and retention. Clearer economics can produce better pricing and capital allocation. Reliable validation can prevent investment in features that do not create value. Accurate ownership records can reduce financing friction and protect alignment.

The investor benefits because the opportunity becomes easier to interpret. The founder benefits because the company becomes easier to manage.

The most useful investment questions often expose decisions the company needs to make for itself. When the evidence cannot answer them, the work is larger than preparing for a meeting.

It is part of building the business.

Why Growing Companies Become Harder to Understand

One of the assumptions we rarely question is that businesses become easier to understand as they grow. Larger organizations produce more information than smaller ones—dashboards, financial reports, customer analytics, operational metrics, board presentations, investor updates, departmental KPIs, and increasingly sophisticated reporting systems. From the outside, it seems reasonable to assume that more information should lead to greater clarity.

In practice, I have gradually come to believe the opposite. As organizations grow, they often become more difficult to understand, not because information becomes scarce, but because it becomes increasingly filtered. Every layer that growth adds also adds another layer of interpretation. By the time information reaches the people making strategic decisions, it has been summarized, simplified, categorized, and stripped of the context that gave it meaning. Leadership receives not reality itself, but a carefully assembled representation of reality. This is not the result of incompetence. It is simply the cost of scale.

A founder with ten employees can observe the business directly. They hear customer conversations, notice operational friction, and see problems emerge before they appear in a report. Once the company has one hundred employees, multiple departments, international customers, and several management layers, direct observation becomes impossible. It is gradually replaced by abstraction.

At first, abstraction is enormously helpful. Dashboards reduce complexity. KPIs create a common language. Financial reports allow leadership to compare performance over time. None of these tools is the problem—they are essential. The problem begins when the representation of the business quietly replaces the business itself.

Over time, every growing company develops two distinct versions of itself. The first is the operational company—the one that exists in thousands of daily decisions, customer interactions, engineering trade-offs, hiring choices, and conversations between people trying to solve real problems. The second is the reported company—the one that appears in executive meetings, investor updates, quarterly reviews, and management presentations. Healthy organizations keep these versions closely aligned. Less healthy organizations allow the distance between them to grow without noticing.

This gap helps explain why successful companies sometimes appear to deteriorate almost overnight. From the outside, the collapse seems sudden. Revenue may have continued to grow. Hiring may have accelerated. Investors may have remained optimistic. Yet internally, the organization had already been changing for months, sometimes years. Decision-making became slower. Temporary workarounds became permanent processes. Teams stopped solving root causes and became skilled at managing symptoms instead. None of these developments necessarily appeared in the metrics that leadership reviewed every week.

Numbers rarely lie, but they rarely tell the whole story either. A company may report record revenue while becoming less profitable to serve each customer. It may recruit exceptional people while making it increasingly difficult for those people to work effectively together. It may successfully launch new products while accumulating technical and operational debt that will eventually slow every future initiative. Each individual metric can be accurate, while the overall picture becomes misleading.

I have become increasingly skeptical of discussions that reduce business performance to a handful of numbers. Metrics matter enormously, but they acquire meaning only within the system that produces them. Two companies can report identical revenue growth while moving in completely different directions. One may be building stronger capabilities with every quarter. The other may simply be postponing problems that have not yet become visible in financial results. Looking only at the numbers, they appear similar. Structurally, they are becoming opposite businesses.

The greatest challenge for leadership is not making decisions but maintaining an accurate understanding of the organization that those decisions affect. Growth continuously increases the distance between reality and perception. Every new reporting layer, every additional management level, and every new operational process makes that challenge more difficult. Information continues to flow, but understanding becomes increasingly dependent on how that information is interpreted rather than how much of it exists.

This may explain why experienced leaders develop healthy skepticism toward certainty. They know that confidence and visibility are not the same thing. A polished presentation can coexist with deep operational confusion. Excellent quarterly results can mask weakening fundamentals. A company can appear highly organized while relying on dozens of invisible workarounds that only a handful of employees fully understand.

I have become less interested in collecting more information and more interested in understanding how organizations produce the information they rely on. Reports, dashboards, and presentations deserve attention, but so do the conversations, assumptions, and decisions that shaped them. The latter are usually harder to observe, yet they often explain far more about the future than the numbers themselves.

The businesses that impress me most are not those with the most sophisticated reporting systems. They are the ones who continue finding ways to stay close to operational reality as they grow. They recognize that scale inevitably creates distance, and they work deliberately to reduce it. They remain curious about what their metrics cannot explain, and they treat unexpected results as invitations to investigate rather than confirmations of existing beliefs.

Growth makes organizations larger. It does not automatically make them more understandable. In many cases, it does exactly the opposite. The longer I work with businesses, the more I believe that one of leadership’s most important responsibilities is protecting the organization’s ability to see itself clearly. Once that ability begins to fade, almost every other problem becomes harder to recognize, harder to explain, and eventually, much harder to solve.

AI Has Made Startups Easier to Build—and Harder to Evaluate

Artificial intelligence has made it possible for very small teams to produce what once required an entire company. A few founders can now build a credible product, create a polished website, prepare an investor presentation, generate market research, and begin acquiring customers with remarkably little capital. This is real progress. It also creates a less obvious problem for investors: the visible quality of a startup has become a weaker indicator of the quality of the business behind it.

A polished product once suggested that a team had overcome meaningful technical, operational, and financial constraints. Today, it may simply indicate that the founders know how to use the tools now available to everyone. The prototype may be convincing. The presentation may be coherent. The early metrics may appear promising. None of this necessarily tells an investor whether the underlying company is durable.

Capital has moved aggressively toward AI. According to Carta, AI companies received roughly 40% of the startup capital recorded on its platform in 2025. In early 2026, that figure reached 54%. At the same time, the median seed-stage company on Carta now has only four employees, illustrating how much smaller early teams have become. The concentration at the top is even more striking. The Q2 2026 PitchBook–NVCA Venture Monitor reports that AI accounted for 86% of US venture dollars invested during the first half of the year, with deals of $100 million or more capturing 87.5% of all capital deployed. The market is setting records, but those records describe a narrow part of the ecosystem.

These numbers are often interpreted as evidence that investors need to move faster. That conclusion is only partially correct. Speed matters when genuinely exceptional opportunities attract immediate competition. But greater speed applied to a weaker evaluation process does not create an advantage. It simply allows mistakes to occur sooner. The more useful question is not how investors can process opportunities faster, but how they can reduce the cost of understanding each opportunity without reducing the quality of judgment.

For years, investors developed practical shortcuts for evaluating young companies. The quality of the product suggested something about the team’s technical ability. The quality of the materials suggested something about the founders’ preparation. Early operational progress suggested something about execution capacity. None of these signals was perfect, but they helped investors form an initial view. AI weakens many of those relationships. A founder can now produce a sophisticated prototype without having built a strong engineering organization. A professional-looking market analysis may contain little original research. Financial projections can be internally consistent while resting on assumptions that have never been tested. This does not mean that founders are attempting to mislead investors. In most cases, they are simply using available tools effectively. The problem is structural. When technology improves the presentation layer faster than the underlying business, surface quality becomes less useful as evidence.

Investors must therefore look more carefully at the distance between what a company can demonstrate and what it has actually established. Before the first founder meeting, the real challenge occurs. An investor must determine what the submitted materials actually establish, what remains unsupported, where the important assumptions are located, and which questions deserve limited meeting time. This is not due diligence—it is investment screening. The distinction matters because the objectives are different. Due diligence asks whether an investment should proceed. Screening asks what deserves attention next.

A good first review should not attempt to predict whether the startup will succeed. Early-stage companies contain too much uncertainty for that degree of confidence. It should identify the structure of that uncertainty. Which claims are supported by evidence? Which results depend heavily on founder interpretation? Which assumptions connect the product to the proposed market? Which numbers describe demonstrated behavior, and which describe expectations? What must be clarified before the opportunity can be evaluated responsibly? These questions are more valuable than a premature score because they improve the next conversation without pretending to eliminate uncertainty.

There is an obvious temptation to solve the screening problem with more AI. Upload the pitch deck. Analyze the company. Generate a score. Predict the outcome. This approach is attractive because it appears to match the scale of the problem. Unfortunately, it also risks introducing false precision into an environment where the available evidence is incomplete, selectively presented, and difficult to compare. An early-stage investment is not a standardized dataset. It is a developing business described through documents created largely by the people raising the capital.

AI can help extract facts, compare statements, identify inconsistencies, organize financial information, and prepare questions. These are valuable capabilities because they reduce repetitive work. What AI cannot do is assume responsibility for judgment. The investor must still decide which evidence matters, how much uncertainty is acceptable, whether the founders’ explanations are credible, and whether the opportunity fits the investor’s own strategy. Technology can make those decisions better informed. It cannot make them objective.

As startup production becomes cheaper, investors will see more companies that look plausible. That does not necessarily mean they will see more companies worth funding. The scarce resource is shifting from access to information toward disciplined attention. Investors who can structure the first review, identify the few questions that materially affect the opportunity, and enter founder conversations with a clear understanding of what remains unknown will have an advantage over those who simply process more decks. The purpose of screening is not to make the investment decision. It is to make the next hour more valuable. AI may continue making startups faster to build, smaller to operate, and easier to present. Those changes are likely to continue. But they do not reduce the importance of investment judgment. They increase it.

The Anatomy of Structural Friction: What Revenue Acceleration Tends to Hide

When an expansion-stage startup begins scaling customer acquisition aggressively, the top-line revenue metrics create a powerful sense of operational comfort across leadership and boards. Upward-trending sales charts, successful funding rounds, access to capital—these create reinforcement that the underlying business model is fundamentally healthy and repeatable. In operational reality, this momentum often serves as a mask for systemic decay. The failure loop does not announce itself with a sudden revenue drop. Instead, it accumulates quietly in the growing gap between high-level strategic intent and what actually happens on the execution floor every day.

The more I observe scaling companies, the more I notice that rapid volume expansion without a stabilized, engineered system logic simply forces an organization to scale its manual workarounds. In the early days, a company survives on founder stamina, tribal knowledge, and direct proximity to every critical transaction. When transaction volume multiplies, this dependency hits a hard physical ceiling. To bridge the execution gaps and prevent customer churn, teams naturally begin inventing shadow processes—fragmented communication channels, isolated spreadsheets, unauthorized workflows—just to fulfill basic daily commitments. The business stops running on engineered infrastructure and begins running on an override culture where every employee operates by their own set of rules.

Nobody calls a meeting to decide this. It simply happens. A customer escalates, and someone writes a script to fix it. A report breaks, and someone builds a parallel spreadsheet. Communication needs to tighten, and someone starts a side Slack channel outside official channels. Each solution is practical. Each solves an immediate problem. Together, they create a parallel operating system that nobody intentionally designed and nobody fully understands.

The structural crisis emerges because the administrative overhead required to coordinate, fix, and align these ad hoc patches grows exponentially. While executive dashboards show record expansion, the core delivery team quietly drowns in exceptions. Every day becomes firefighting. Senior leadership becomes tactical traffic routers, managing symptoms instead of building capability. The business model has transformed from something engineered into something fragile—a high-risk operation that is increasingly expensive to maintain and impossible to audit.

What makes this dangerous is that the visible metrics remain strong. Revenue continues climbing. Customer acquisition keeps accelerating. The business looks healthy precisely when it is accumulating the most operational debt. Leadership sees the growth data and concludes that things are working. The teams running the actual operation know better. They are working sixty-hour weeks managing workarounds. The gap between what leadership believes and what is actually happening grows wider every quarter.

By the time contradictions become visible—when margins compress, churn accelerates, or execution suddenly becomes impossible—the structural debt has usually become too expensive to reverse. The company has already hired teams designed to manage the broken system. It has built processes around the workarounds. It has made strategic commitments based on operating assumptions that no longer reflect reality.

True operational resilience requires shifting management focus away from lagging growth indicators and toward independent validation of the internal business physics while there is still time to change direction. Not after the revenue picture changes. Before. During the period when everything appears to be working, that is exactly when leadership should be most skeptical about whether it actually is.